New Launches · News
1,716 New Homes Sold in October: Thomson Reserve Leads, Lucerne Grand Follows
Singapore New Private Home Sales Hit 2026 High in October, with Thomson Reserve Contributing 60% of Transactions
After a quiet August and September, Singapore's new private home market rebounded clearly in October.
According to data released by the Urban Redevelopment Authority (URA) on 16 November, developers sold 1,716 new private homes in October, excluding executive condominiums (ECs) — about 5.8 times the 296 units sold in September, and the highest monthly sales figure of 2026.
However, sales were still 29.2% lower than the 2,424 units sold in October 2025. This means the market, while clearly recovering from the previous two months, has not yet returned to last year's transaction levels.
Concentrated New Launches Drive the Rebound
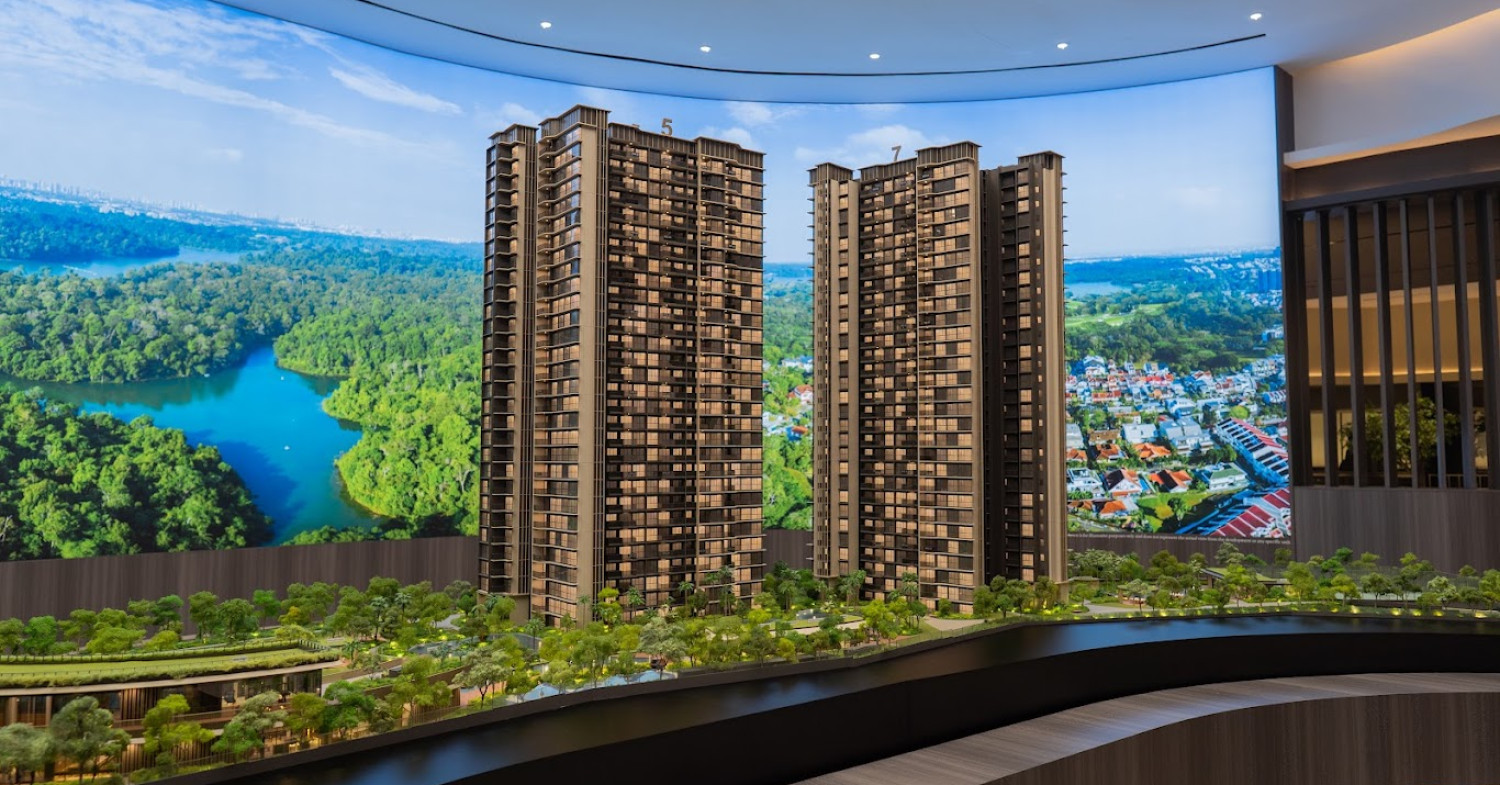
October's rebound was linked to developers launching the year's final batch of major projects, including Thomson Reserve, Lucerne Grand and The Serra Residences, as well as additional units released at Dunearn House.
Developers launched 2,058 new private homes during the month — more than 13 times the 158 units in September — also the highest monthly supply of the year. Compared with the same period last year, however, launch volume was still down 7.8%.
Market analysts consider this rebound expected. The return of large projects gave previously wait-and-see buyers more options and helped release some pent-up demand.
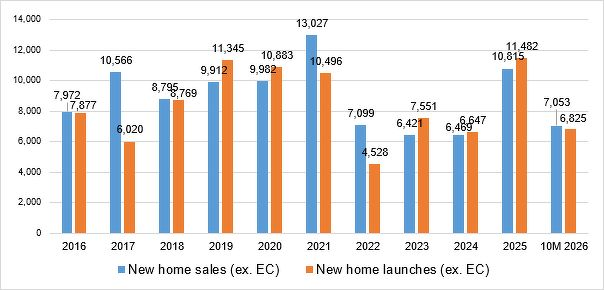
| Year | New home sales (ex. EC) | New home launches (ex. EC) |
|---|---|---|
| 2016 | 7,972 | 7,877 |
| 2017 | 10,566 | 6,020 |
| 2018 | 8,795 | 8,769 |
| 2019 | 9,912 | 11,345 |
| 2020 | 9,982 | 10,883 |
| 2021 | 13,027 | 10,496 |
| 2022 | 7,099 | 4,528 |
| 2023 | 6,421 | 7,551 |
| 2024 | 6,469 | 6,647 |
| 2025 | 10,815 | 11,482 |
| 10M 2026 | 7,053 | 6,825 |
Thomson Reserve Sold 1,029 Units, About 60% of the Month's Sales
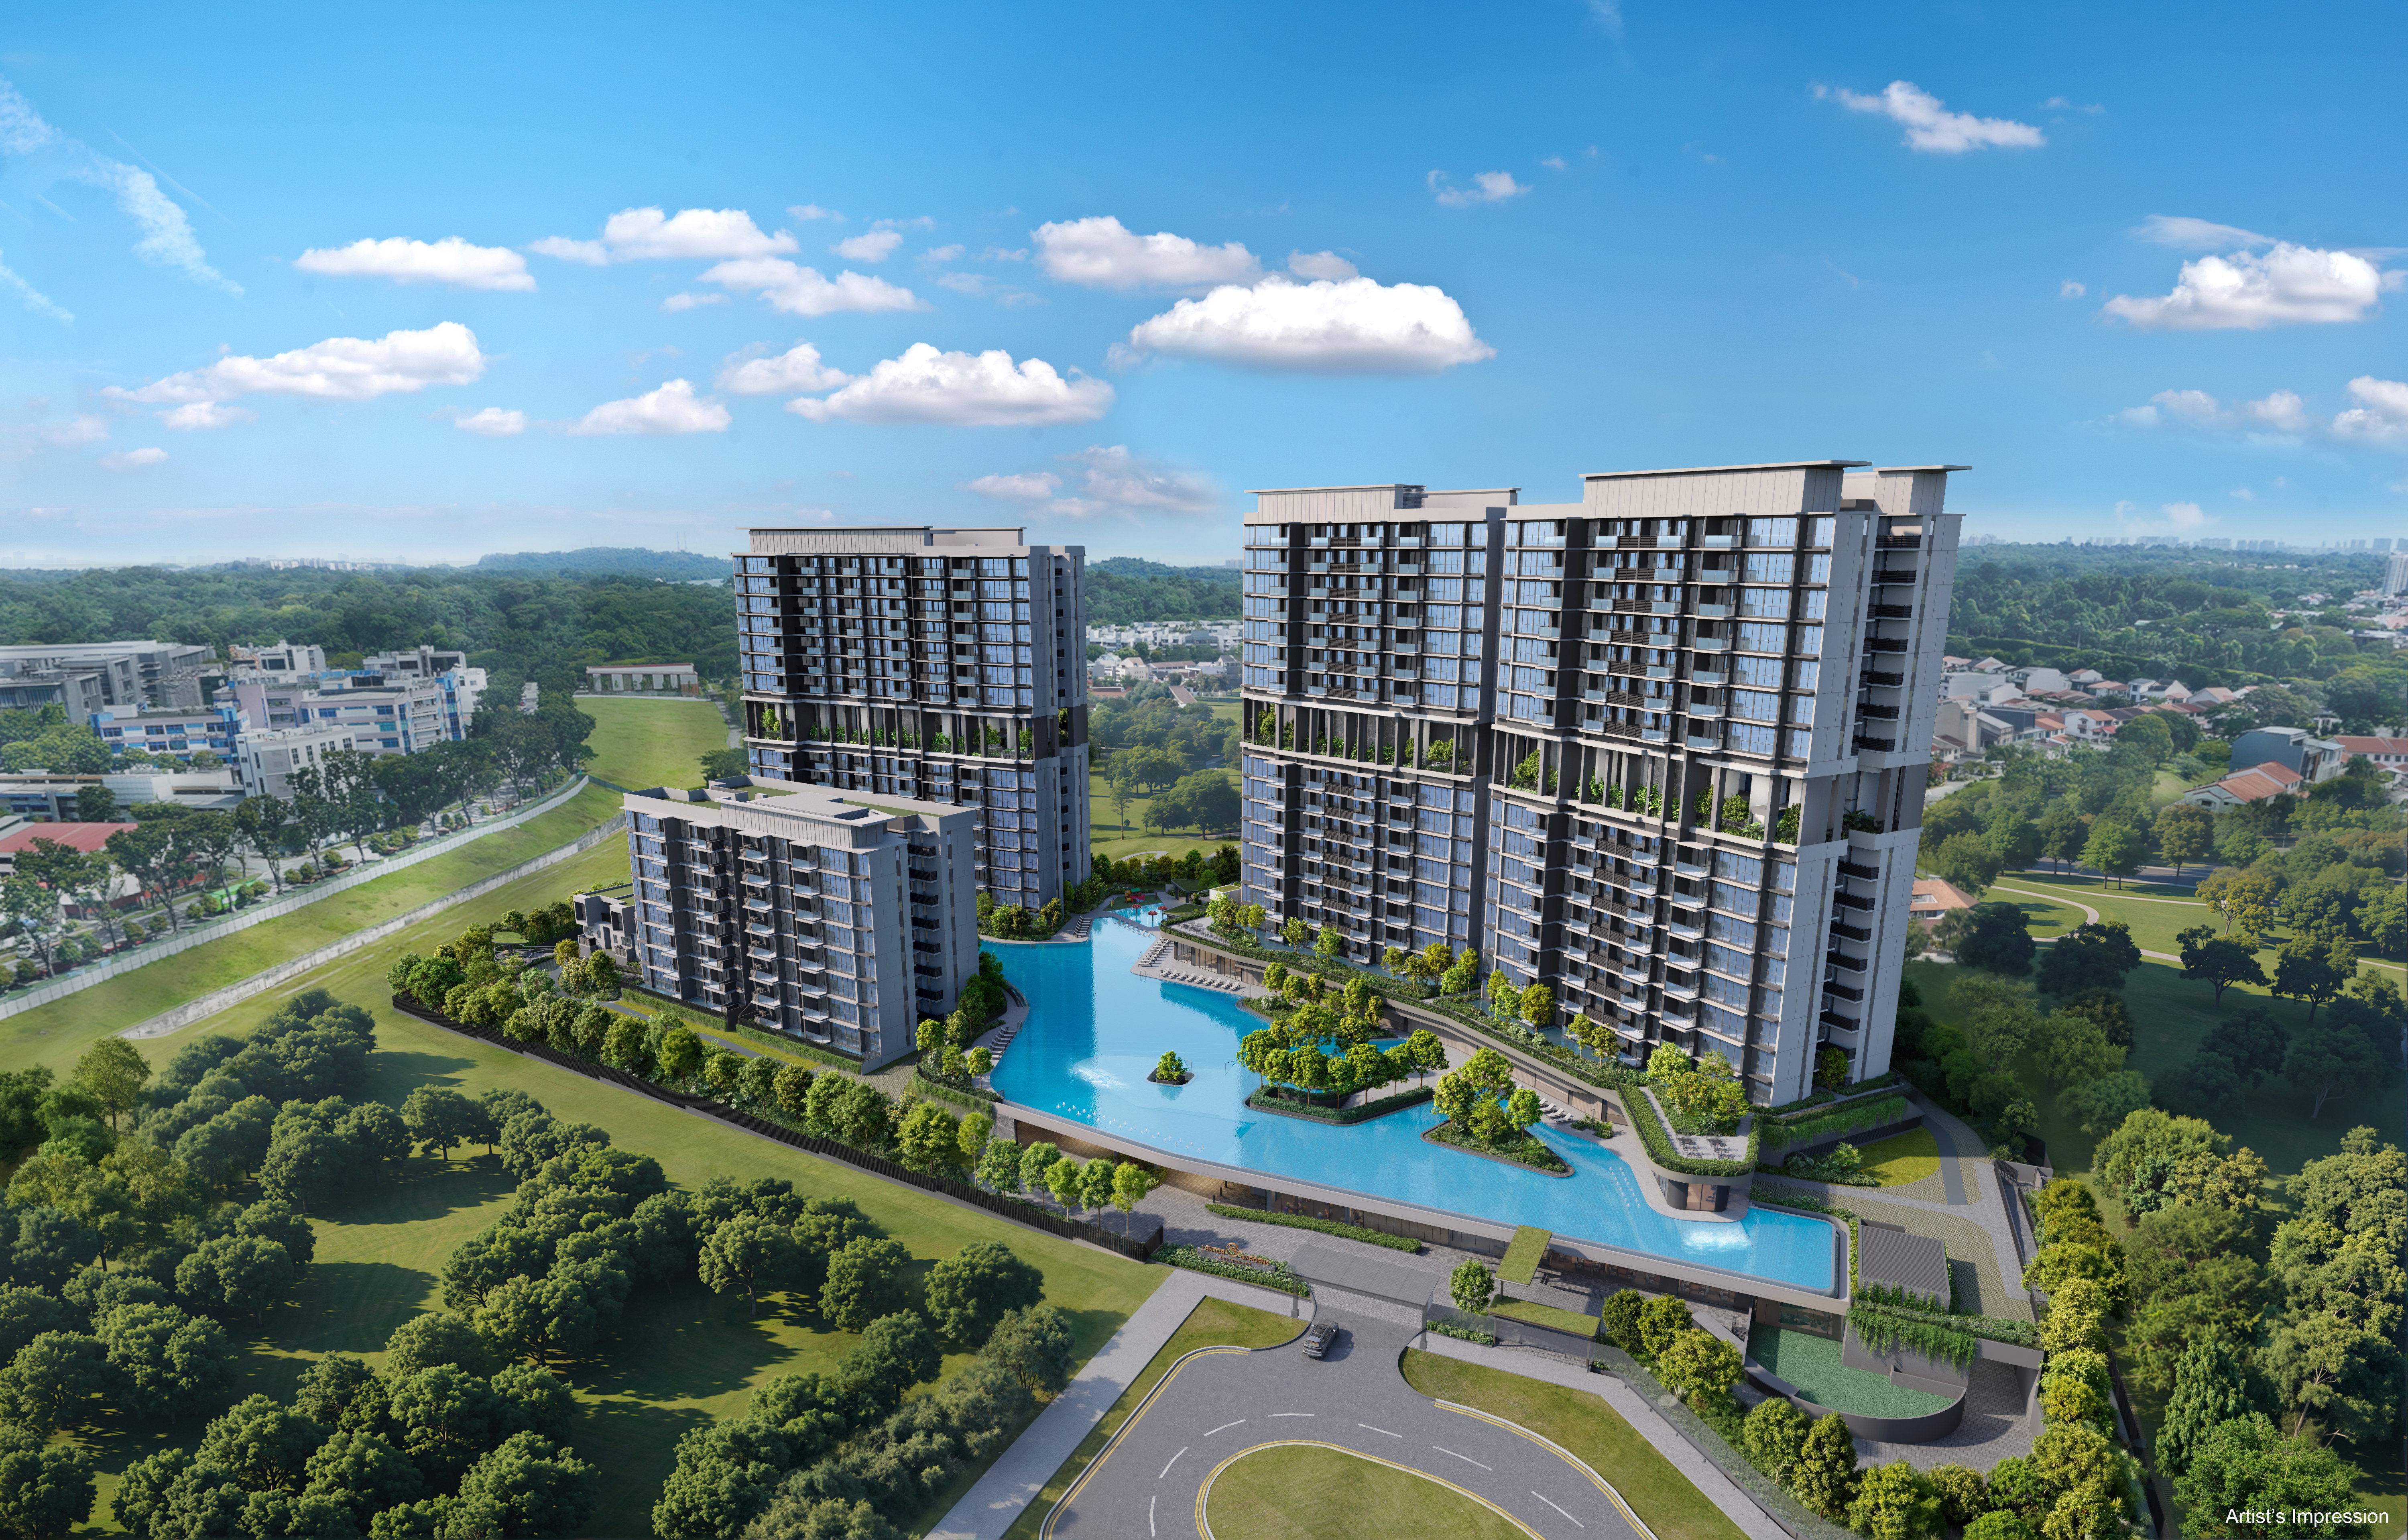
Located at Bright Hill Drive in the Rest of Central Region (RCR, city fringe), Thomson Reserve was October's best-selling new launch.
According to the month's statistics, the project sold 1,029 units — about 81% of its total units — at a median transacted price of S$2,865 psf, accounting for roughly 60% of islandwide new private home sales that month.
For comparison, islandwide new private home sales in Q3 2026 totalled 1,180 units. Thomson Reserve's October sales alone equalled about 87% of the entire previous quarter's islandwide volume.
Analysts attribute the project's appeal to several factors:
- Proximity to the Thomson–East Coast MRT line, with convenient transport;
- Mature amenities in the Upper Thomson area, with schools, dining and daily facilities nearby;
- A large development offering a wide range of facilities and unit types;
- Pricing in line with the prevailing market environment.
In addition, Upper Thomson had not seen a large condominium launch of comparable scale since JadeScape in 2018. Limited new supply in the area may have built up demand from buyers wishing to stay in a familiar neighbourhood.
Note that URA's monthly statistics and developers' launch-day booking figures may differ due to timing and recording methods, and should not be directly conflated.
Lucerne Grand Sold 393 Units, with Quantum in the Spotlight
Located in Jurong West in the Outside Central Region (OCR, suburbs), Lucerne Grand ranked second with 393 units sold, at a median transacted price of S$2,496 psf.
As the first new residential project in the Lakeside area in about a decade, Lucerne Grand offered a fresh option for buyers looking to purchase in this part of Singapore.
Notably, nearly 80% of the units sold during the month were priced below S$2.5 million in total. Analysts believe this price quantum closely matched the budgets of many suburban buyers and was a key factor in the project's sales performance.
This reflects that buyers look beyond per-square-foot pricing — they also weigh total price, space configuration, and what the household can afford.
Other Projects Saw Steady Sales, but Momentum Was Uneven
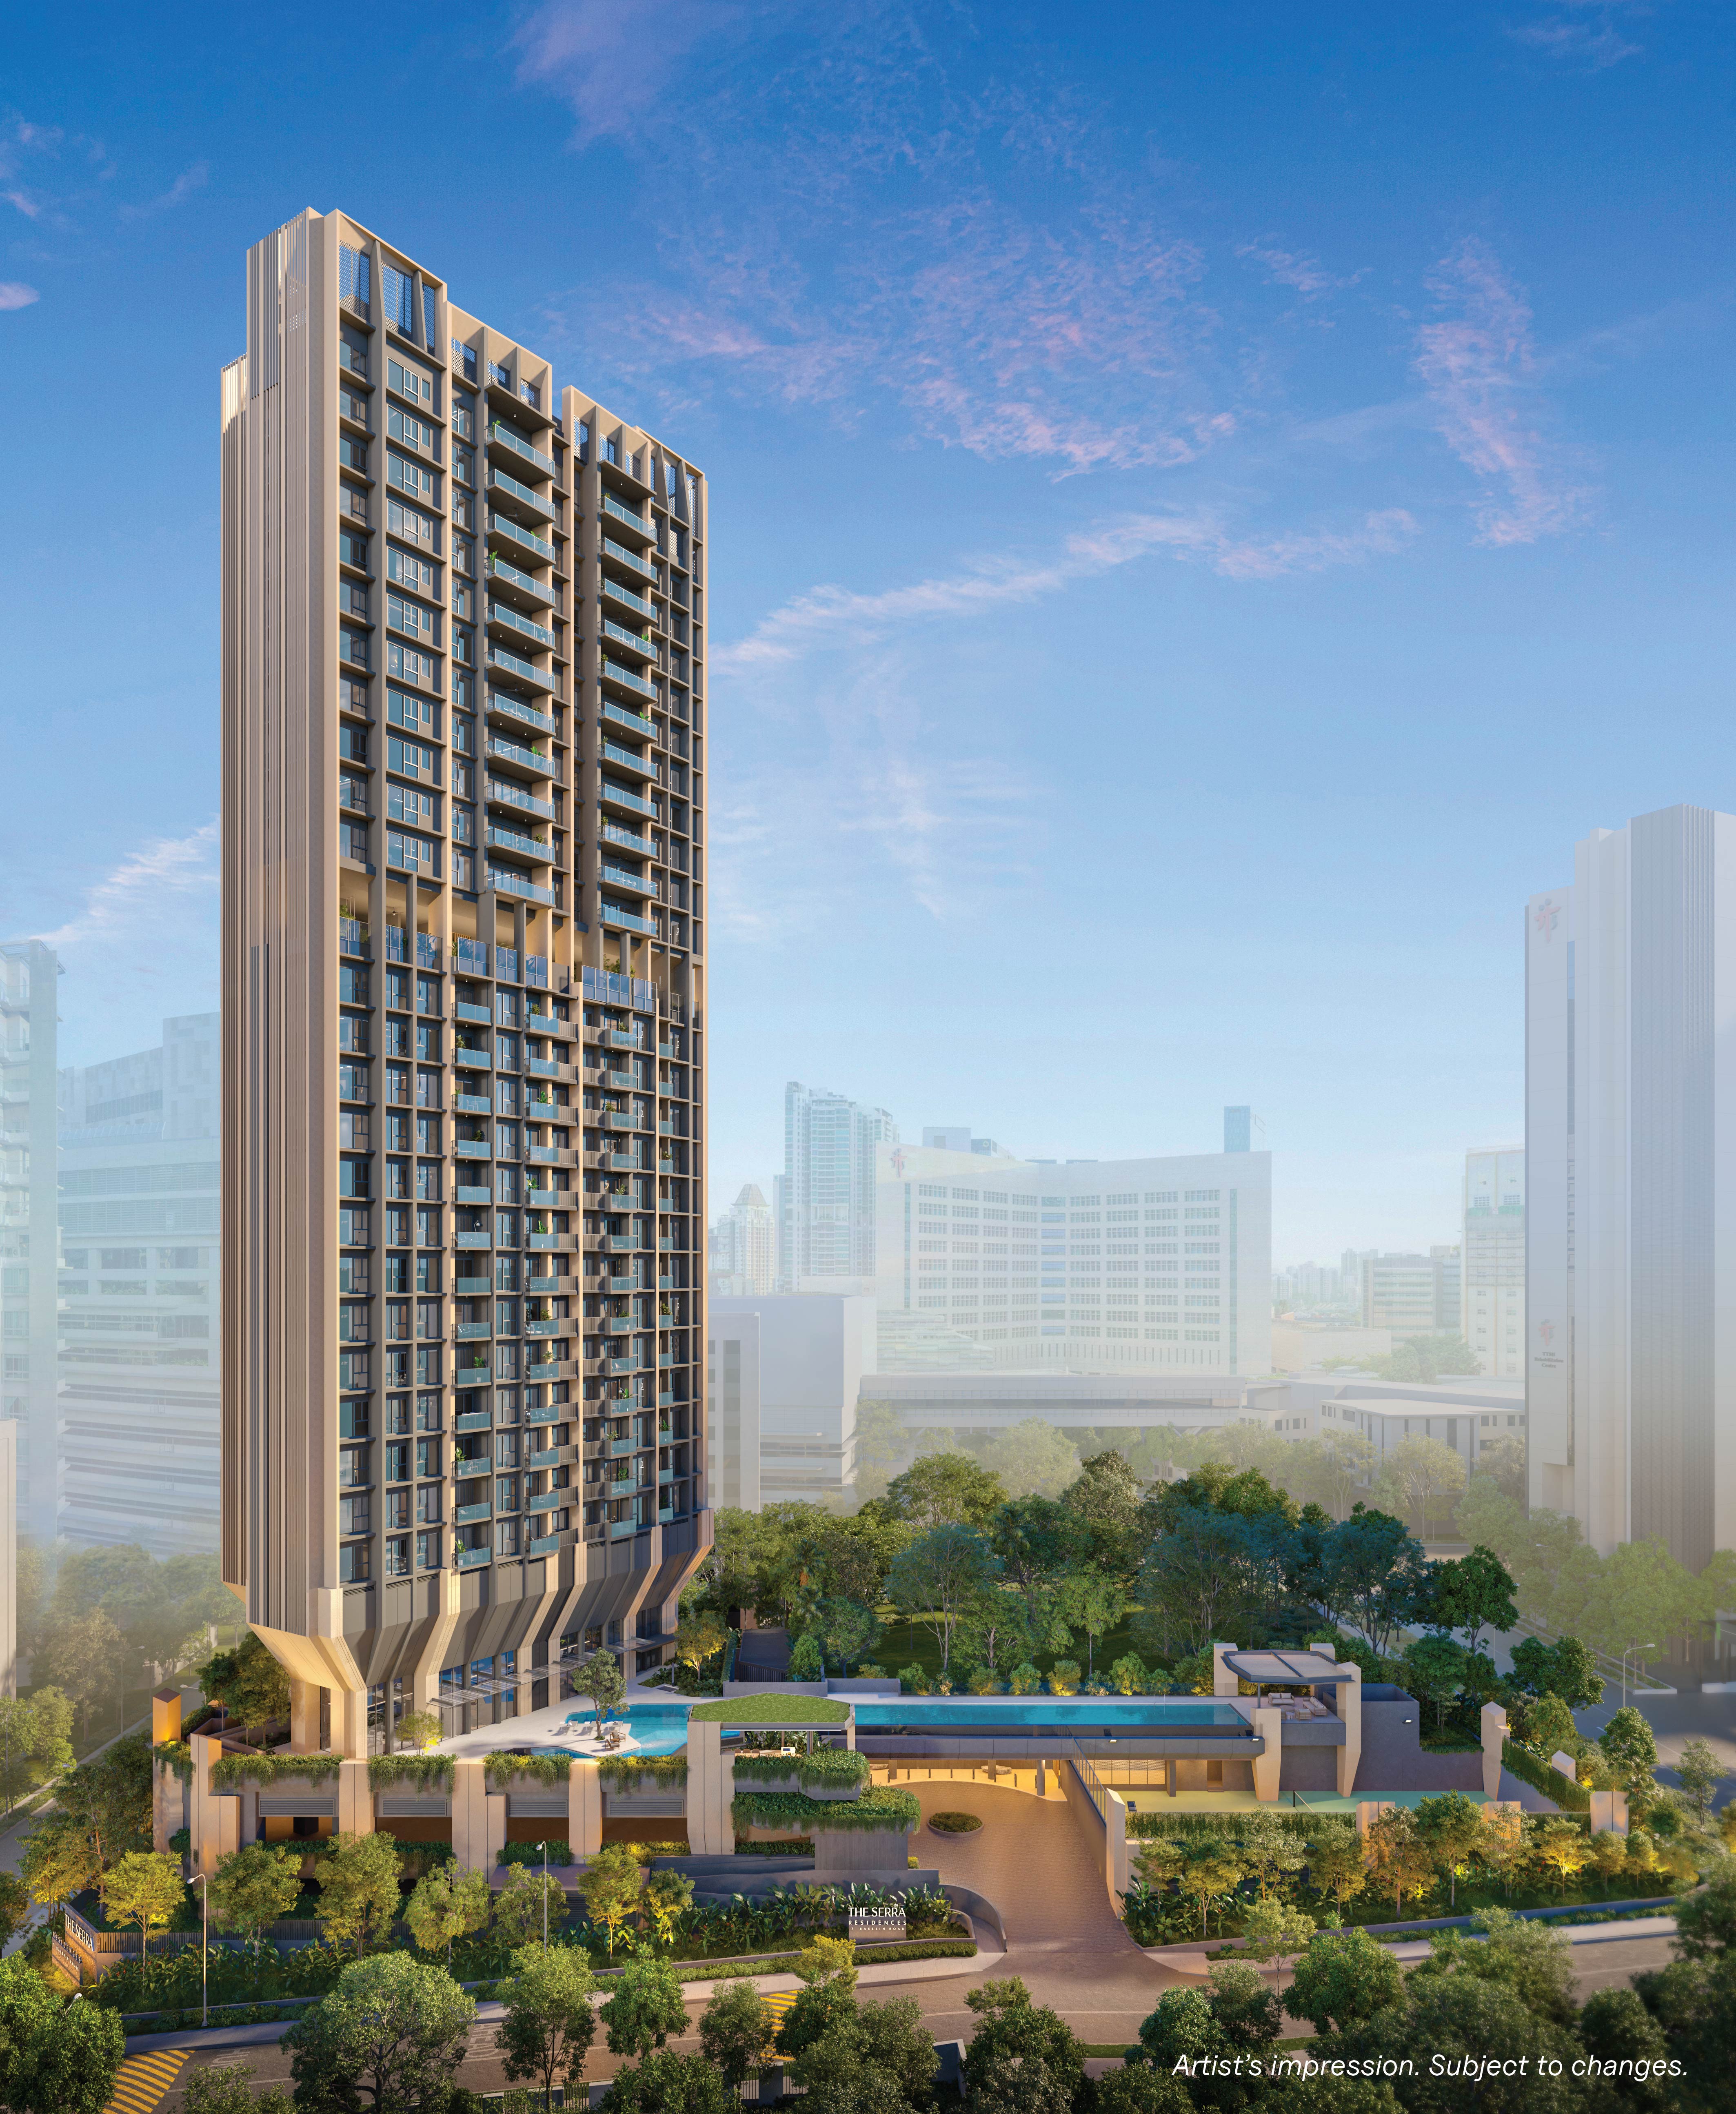
The Serra Residences, a freehold project in District 11 near the HealthCity Novena medical hub, sold 25 units in October — including a penthouse — at a median transacted price of S$3,311 psf.
Other relatively active projects included:
- Union Square Residences: 41 units sold, median S$2,869 psf;
- Dunearn House: 27 units sold, median S$3,108 psf;
- Lentor Gardens Residences: 21 units sold, median S$2,414 psf.
Beyond the major launches, however, transactions at many previously launched projects remained relatively moderate.
Analysts note that buyers are still entering the market, but are choosing more carefully. Beyond price, location and facilities, they also consider future financing costs, employment prospects, and the household's financial capacity.
October's rebound therefore reflects demand concentrating on selected projects, rather than broad-based strength across all developments.
City Fringe Accounted for Nearly 70% of Sales
By region, October's new private home sales were concentrated in the city fringe:
| Region | October sales | Share of total sales |
|---|---|---|
| Rest of Central Region (RCR) | 1,157 units | 67.4% |
| Outside Central Region (OCR) | 488 units | 28.4% |
| Core Central Region (CCR) | 71 units | 4.1% |
Figures may not add up to 100% due to rounding.
Led by Thomson Reserve, RCR sales jumped from 131 units in September to 1,157 — the region's highest monthly volume since October 2025.
The OCR recorded 488 transactions, the highest since April 2026. With projects such as Chencharu Central Residences, One Chuan Grove and Lentor Signature planned for launch, suburban transactions are expected to rise further in Q1 2027.
CCR sales rose from 40 units in September to 71, with Dunearn House the standout performer. The next major wave of CCR supply is not expected until Q1 2027, when The River Opus may launch.
October's Best-Selling New Launches at a Glance
The table below shows transaction data for some of October's best-selling projects. Prices are the month's transacted psf figures and do not represent current asking prices for remaining units.
| Project | Region | Units sold | Median psf | Lowest psf | Highest psf |
|---|---|---|---|---|---|
| Thomson Reserve | RCR | 1,029 | $2,865 | $2,608 | $3,351 |
| Lucerne Grand | OCR | 393 | $2,496 | $2,252 | $2,632 |
| Union Square Residences | RCR | 41 | $2,869 | $2,660 | $3,141 |
| Dunearn House | CCR | 27 | $3,108 | $2,853 | $3,386 |
| The Serra Residences | CCR | 25 | $3,311 | $3,123 | $4,200 |
| Lentor Gardens Residences | OCR | 21 | $2,414 | $2,305 | $2,540 |
| One Marina Gardens | RCR | 14 | $3,071 | $2,925 | $3,290 |
| Narra Residences | OCR | 13 | $2,148 | $2,084 | $2,411 |
| Chuan Park | OCR | 10 | $2,680 | $2,641 | $2,726 |
| Hudson Place Residences | RCR | 10 | $2,618 | $2,529 | $2,691 |
Big-Ticket Deals Still Found Buyers
October's highest-value new home transaction was a detached house on Bournemouth Road in District 15, purchased by a Singaporean buyer for S$15.7 million.
Other large transactions included:
- A penthouse at The Serra Residences, purchased by a permanent resident for S$11.2 million;
- A semi-detached house on Woo Mon Chew Road, purchased by a Singaporean buyer for S$10.4 million.
These deals show that demand persists for high-quantum homes, though individual large transactions do not represent the performance of the entire high-end market.
EC Sales Stayed Quiet, Mainly Due to Limited Available Supply
In contrast to the rebound in private new launches, the EC market was relatively quiet in October.
Developers sold 15 new EC units during the month, down 34.8% from 23 in September, at a median transacted price of S$1,829 psf.
Of these, Coastal Cabana sold 14 units at a median of S$1,820 psf, leading EC sales for the fifth consecutive month; the other transaction came from Rivelle Tampines.
Analysts attribute the low volume mainly to the absence of major new launches and dwindling available units at existing projects.
As of end-October, only 137 unsold units remained across launched EC projects. Low sales alone therefore do not indicate that buyers have lost interest in ECs.
Next, City Developments' 430-unit Wynwood Grand is expected to open for e-applications in December, with bookings starting in January 2027. It will be Woodlands' first new EC project since 2014.
Reports also note the project is expected to be among the last batches of ECs still subject to the five-year minimum occupation period and eligible for the deferred payment scheme. Specific conditions should be verified against official sales documents and regulations.
Other ECs to watch in 2027 include Solano Grand at Senja Close, Clovelle of Woodlands, and projects at Sembawang Road and Miltonia Close. Together with Wynwood Grand, these are expected to bring close to 2,000 new EC units to the market.
Year-End Sales Expected to Slow; 2027 Could Bring Far More Choice
Despite October's yearly high, cumulative full-year sales remain below last year's.
According to report estimates, in the first ten months of 2026:
- Developers sold about 7,053 new private homes, down 31.5% year-on-year;
- Cumulative launches totalled about 6,825 units, down 38.4% year-on-year.
With the school holidays, overseas travel and the festive season approaching, developers generally scale back major launches, and buyers may defer decisions. November's main new supply is expected to include The Park Residence on Stevens Road — a freehold luxury project of just 43 units, with homes exceeding 4,000 sq ft.
With reduced new supply, the market expects November developer sales to fall back to around 200–300 units.
For the full year, forecasts cited in reports suggest: new private home sales of up to about 7,400 units, launches of about 6,900 units, and private home prices rising about 3% to 4% for the year. If realised, 2026 would be the first year since 2022 in which full-year sales exceed that year's launch volume.
Looking ahead to 2027, the market estimates that more than 30 launch-ready projects could bring about 16,800 homes; excluding ECs, about 14,800.
Notable upcoming supply includes the integrated development Hougang Central Residences, and future projects on the second Government Land Sales sites at Bayshore Drive and Dunearn Road. Actual launch timing and unit counts remain subject to developers' announcements.
For buyers, more supply means more room for comparison. Beyond headline sales figures, it pays to return to one's own budget, layout needs, transport requirements and purchase timeline to judge which project best suits long-term holding and living.
Projects in this article
CCR · Core Central
The Serra Residences
District 11 | Newton / Novena
Price: From $2,266,264
OCR · Outside Central
Thomson Reserve
District 20 | Ang Mo Kio / Bishan / Thomson
Price: From $1,643,000
CCR · Core Central
Dunearn House
District 11 | Newton / Novena
Price: From $1,538,000
OCR · Outside Central
Lucerne Grand
District 22 | Boon Lay / Jurong / Tuas
Price: From $1,519,000
RCR · Rest of Central
Union Square Residences
D1 | Havelock Road
Price: From $1,307,000
OCR · Outside Central
Lentor Gardens Residences
District 26 | Mandai / Upper Thomson
Price: From $1,594,900