News
Private Resale Market Outlook: Growth Moderates but Demand Remains Resilient
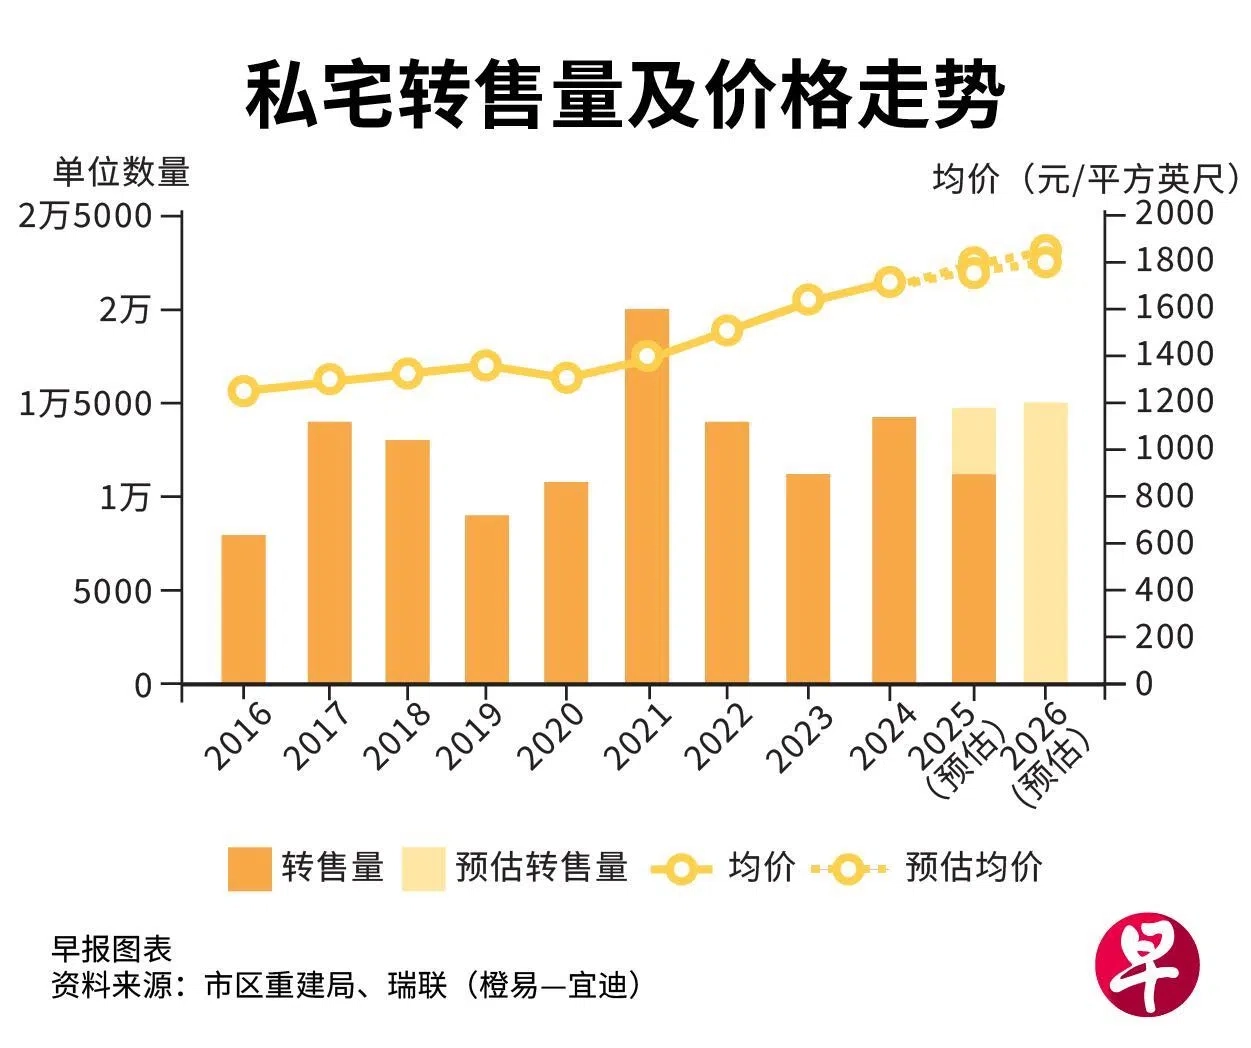
Although price growth in Singapore's private home resale market moderated for the fourth consecutive year, full-year growth is still projected to reach 4% to 5%, largely on par with the new private home market. Over the past decade, resale private homes have registered an average annual price increase of around 4.3%, lower than the 8.0% recorded by new launches, indicating that new projects continue to see stronger price momentum.

Market analysts point out that resale demand is expected to remain resilient in 2025, underpinned by more project completions and easing interest rates. Data indicates that the average transacted unit price for resale private homes this year is projected to hover just below $1,800 psf. Over the past three years, resale prices rose by 8.7%, 7.5%, and 5.1% respectively, reflecting a gradual slowdown in growth, though overall price levels have continued to trend steadily upwards.
Notably, despite robust new launch sales in 2024—where full-year volumes are projected to jump from 6,469 units in 2023 to around 11,000 units—the resale market was not cannibalised. Resale transaction volumes still exceeded 14,000 units, comparable to last year. This demonstrates that new launches and the resale market cater to different demand bases, allowing both segments to expand in tandem.
A key factor supporting the market is the ongoing improvement in the interest rate environment.
The 3-month compounded Singapore Overnight Rate Average (SORA) is projected to fall by around 1.8 percentage points in 2025, which should significantly lower mortgage payments for homebuyers and bolster affordability. However, attractively priced new launches in the fourth quarter have drawn some prospective buyers away from the resale market. The price gap between new launches and resale properties narrowed from 39.9% in 2023 to approximately 26.5% in 2025, with this closing spread encouraging more buyers to opt for new private homes.
Nonetheless, looking at unit sizes, new launches are generally more compact, which keeps per-square-foot (psf) prices for new private homes substantially higher than those in the resale market. SRI data shows that the average transacted price for new private homes in 2025 is expected to exceed $2,560 psf, over 40% higher than in the resale market.
Looking ahead to 2026, analysts widely expect the private resale market to maintain a resilient performance. As more developments obtain their Temporary Occupation Permit (TOP), resale supply will naturally expand. In the Rest of Central Region (RCR), an estimated 3,977 units are slated for completion, offsetting the reduced supply of new launches in the area and helping to support home prices. In contrast, fewer completions are expected in the Outside Central Region (OCR), helping to mitigate price pressures from potential oversupply. SRI forecasts that resale transaction volume in 2026 will hold steady between 14,000 and 15,000 units, with prices expected to register modest gains of 2% to 4%.
Resale transaction volume in 2025 could land between 10,000 and 12,000 units, slightly lower than this year. He noted that factors such as geopolitical uncertainties, shifting tariff policies, slower economic growth, and cautious hiring sentiment could temper homebuyer confidence. While an increasing number of HDB flats reaching their Minimum Occupation Period (MOP) will generate upgrading demand, an estimated 9,729 new private homes are slated for launch in 2025—with 85% located in the RCR and OCR—which could also divert prospective buyers from the resale pool.
Driven by solid underlying fundamentals and a wave of project completions, the resale market is expected to sustain healthy transaction levels in 2026. Approximately 7,006 units are expected to be completed next year, a 33.5% year-on-year increase, bolstering activity in the resale market. Lower interest rates will also lift market sentiment.
However, a sharp spike in resale transaction volume remains unlikely. High land bid prices in recent Government Land Sales (GLS) tenders will elevate future new launch prices, while cooling measures such as ABSD, TDSR, and SSD continue to curb short-term speculative activity, ensuring a stable long-term market structure. Mohan projects resale transaction volume in 2025 to range between 14,500 and 15,000 units.
Overall, while Singapore's private home resale market faces abundant new launch supply and broader macroeconomic uncertainties, it is well-supported by steady underlying demand, an easing interest rate environment, and a stream of project completions, positioning it for moderate, sustainable growth over the next two years.