News
Orchard Boulevard Site Draws Five Bids, Top Bid $1,755 psf ppr: What It Means for the Future Launch
Prime Orchard land draws developers again
On 29 October 2026, URA released the tender results for the Orchard Boulevard private residential site, which drew five bids.
The top bid of about S$181.86 million, or S$1,755 psf ppr, came from a consortium of Intrepid Investments (a Hong Leong Holdings unit) and TID Residential.
It was about 8.3% above the second-highest bid and about 30% above the lowest. Five bidders show prime land is still attractive, while the wide spread suggests developers differ on future pricing and sales risk.
Note: these are tender results; the top bid does not mean the site has been formally awarded.
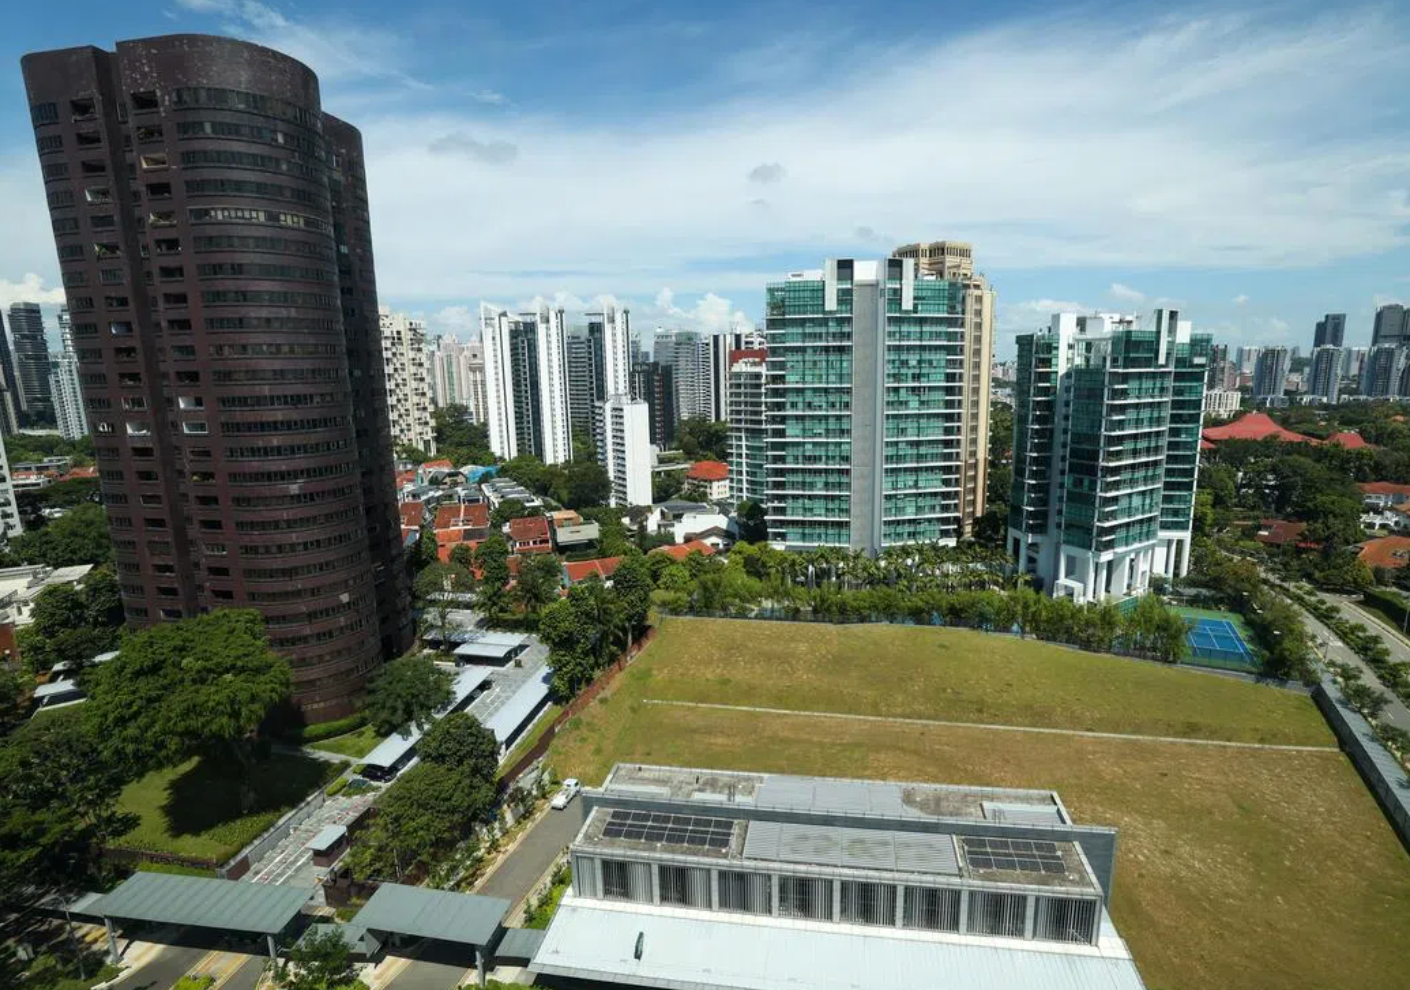
Site overview: near the MRT, about 110 homes
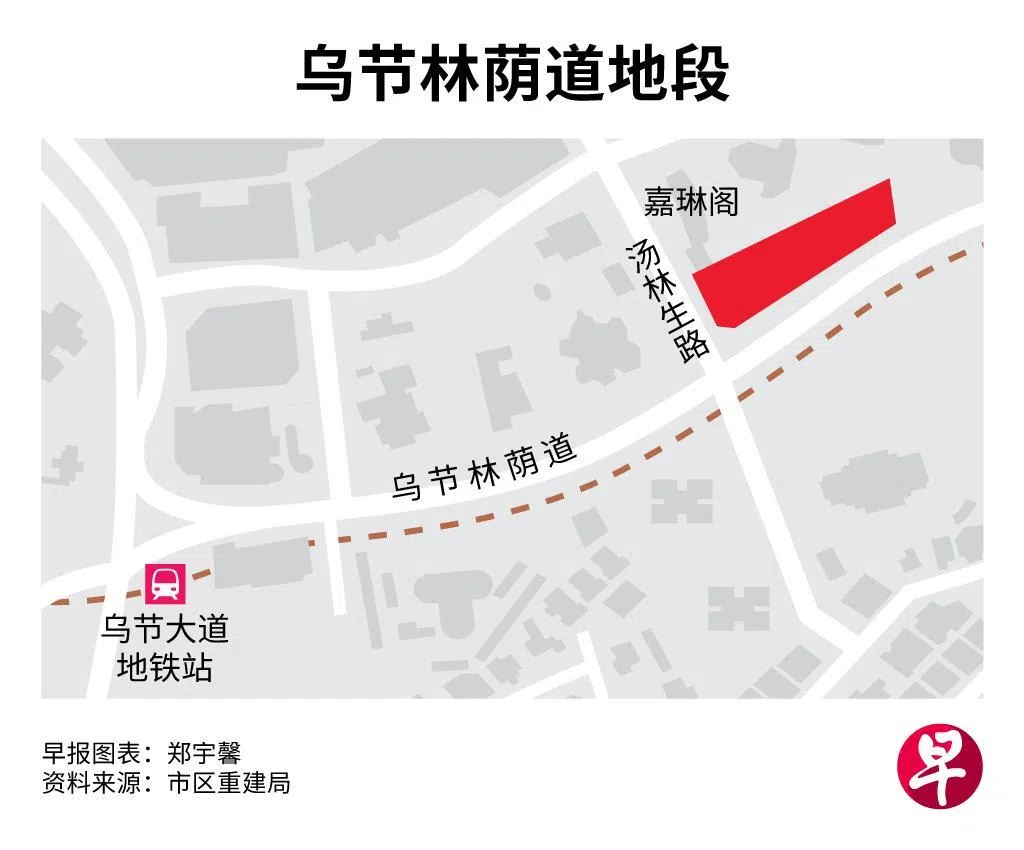
The site is next to Orchard Boulevard MRT station and is one of few private residential sites tendered in the area.
| Item | Details |
|---|---|
| Location | Orchard Boulevard |
| Site area | approx. 3,438 sqm (approx. 37,006 sq ft) |
| Max. gross floor area | approx. 9,627 sqm |
| Estimated homes | approx. 110 |
| Bids received | 5 |
| Top bid | approx. S$181.86 million |
| Top land rate | approx. $1,755 psf ppr |
At about 110 units, future supply will be limited. A small project is not necessarily cheaper to build, though: facilities, basement car park and marketing costs are spread across fewer units.
Wide spread in bids shows divided views
The bids were:
| Bidder | Land rate |
|---|---|
| Intrepid Investments & TID Residential consortium | approx. $1,755 psf ppr |
| GRC Development | approx. $1,620 psf ppr |
| BBR Development, Mindarie Holding & Quartz Capital Group consortium | approx. $1,551 psf ppr |
| Wincove Investment (Wing Tai Holdings) | approx. $1,471 psf ppr |
| Consortium including Macly and Roxy | approx. $1,350 psf ppr |
Five bids were in line with expectations, showing prime sites still attract capital.
But a ~30% gap between the highest and lowest bids indicates different assumptions about pricing potential, development costs and sales pace.
Analysts cited in reports said interest rates, possible cooling measures and new CCR supply could all factor into bids. These are risk considerations, not predictions that such changes will happen.
8.5% above Upperhouse, but below recent Newton sites
The S$1,755 psf ppr bid is best read against several benchmarks.
The neighbouring Upperhouse at Orchard Boulevard site sold in February 2024 at about $1,617 psf ppr; the new top bid is about 8.5% higher.
Compared with two sites near Newton MRT sold in the past year, however, this bid is lower:
| Site | Land rate |
|---|---|
| Orchard Boulevard (this tender) | approx. $1,755 psf ppr |
| Upperhouse site | approx. $1,617 psf ppr |
| Bukit Timah Road near Newton | approx. $1,820 psf ppr |
| Peck Hay Road | approx. $1,865 psf ppr |
Two readings follow:
Land values in Orchard Boulevard have moved up versus the Upperhouse purchase; yet developers did not chase prices higher than the recent Newton sites.
Sites differ in size, planning parameters and tender timing, so these comparisons show trends rather than like-for-like price changes.
Upperhouse sales offer a reference
According to reported data, Upperhouse has sold 249 of its 301 units (about 82.7%) since launching in July 2025, at an average of about $3,405 psf.
This gives developers a reference for local demand and price acceptance, and may support the top bidder's confidence in future pricing.
But Upperhouse's average psf cannot simply be applied to the new site; unit size, floor, facing, specifications and launch timing will all affect final prices.
For buyers, the meaningful comparison is the total price, layout and living conditions of specific units, not project-wide average psf.
More CCR supply ahead, competition worth watching
Beyond existing projects, developers must also weigh upcoming supply.
Reports note that CCR GLS sites sold since November 2025 could together yield about 1,700 new homes, including:
- Bukit Timah Road
- Dunearn Road (second site)
- Holland Plain
- Peck Hay Road
- River Valley Parcel C
These ~1,700 units are expected future supply, not completed or fully launched homes.
As they launch, buyers may have more choice and developers will need to compete on product and price.
On the other hand, the established, affluent resident base nearby may still provide owner-occupier and upgrader demand. More supply does not mean demand disappears; the key is whether new products match buyers' budgets and needs.
Future prices may be $3,400-3,800 psf — still a forecast
Estimates cited in reports suggest the new project could sell above S$3,400 psf, with some forecasting $3,500-3,800 psf and a possible launch in 2028.
These are market forecasts, not developer-announced prices or timelines.
Land bids are quoted in psf ppr and home sales in psf; the bases differ, so subtracting one from the other does not give developer profit.
Future pricing will depend on land, construction, financing and other costs, as well as competition and demand at launch.
What buyers should watch
This tender offers three takeaways.
First, prime core locations remain attractive. Five bids show developers are still willing to evaluate Orchard opportunities.
Second, land bids increasingly reflect project-specific views. The wide spread shows there is no single view on future sales.
Third, buyers should watch both existing projects and future supply. Upperhouse offers sales data while the new site offers a window on future product; compare them against your own purchase timeline.
For buyers interested in Orchard, the next things to follow are the formal award, the project's planning, and actual transactions at nearby new launches. Only once unit mix and prices are released can the new project's competitiveness be judged.