News
No New Launches, No Sales? An Analysis of Singapore's June Private Residential Market Data
First Time in Nearly 20 Years! Zero New Launches in June as Singapore New Home Sales Plunge 65% MoM — Will H2 See a Rebound?
The Singapore private residential market witnessed an exceedingly rare phenomenon this June.
Coinciding with the mid-year school holidays and developers collectively holding back launches during the seasonal lull, June marked the first month with "zero new project launches" since the Urban Redevelopment Authority (URA) began tracking monthly developer sales data in 2007.
Without the catalyst of new launches, primary private home sales fell substantially.
According to flash data released by the URA on 15 July, developers sold 156 new private homes (excluding Executive Condominiums, or ECs) in June 2026, plunging 65.1% from the 447 units moved in May. This also marks the lowest monthly sales tally since February 2024.
Year-on-year (YoY), sales dropped by 42.6%.
However, market analysts broadly agree that this was merely a temporary dip caused by seasonal factors, rather than a sign of fundamentally weakening demand.
No New Launches, Naturally Lower Sales Volume
In fact, June has traditionally been a quiet month for Singapore's property market. With the mid-year school holidays in full swing, many developers opt to defer project launches to wait for more opportune timing.
June this year set an unprecedented record: not a single new project was launched into the market.
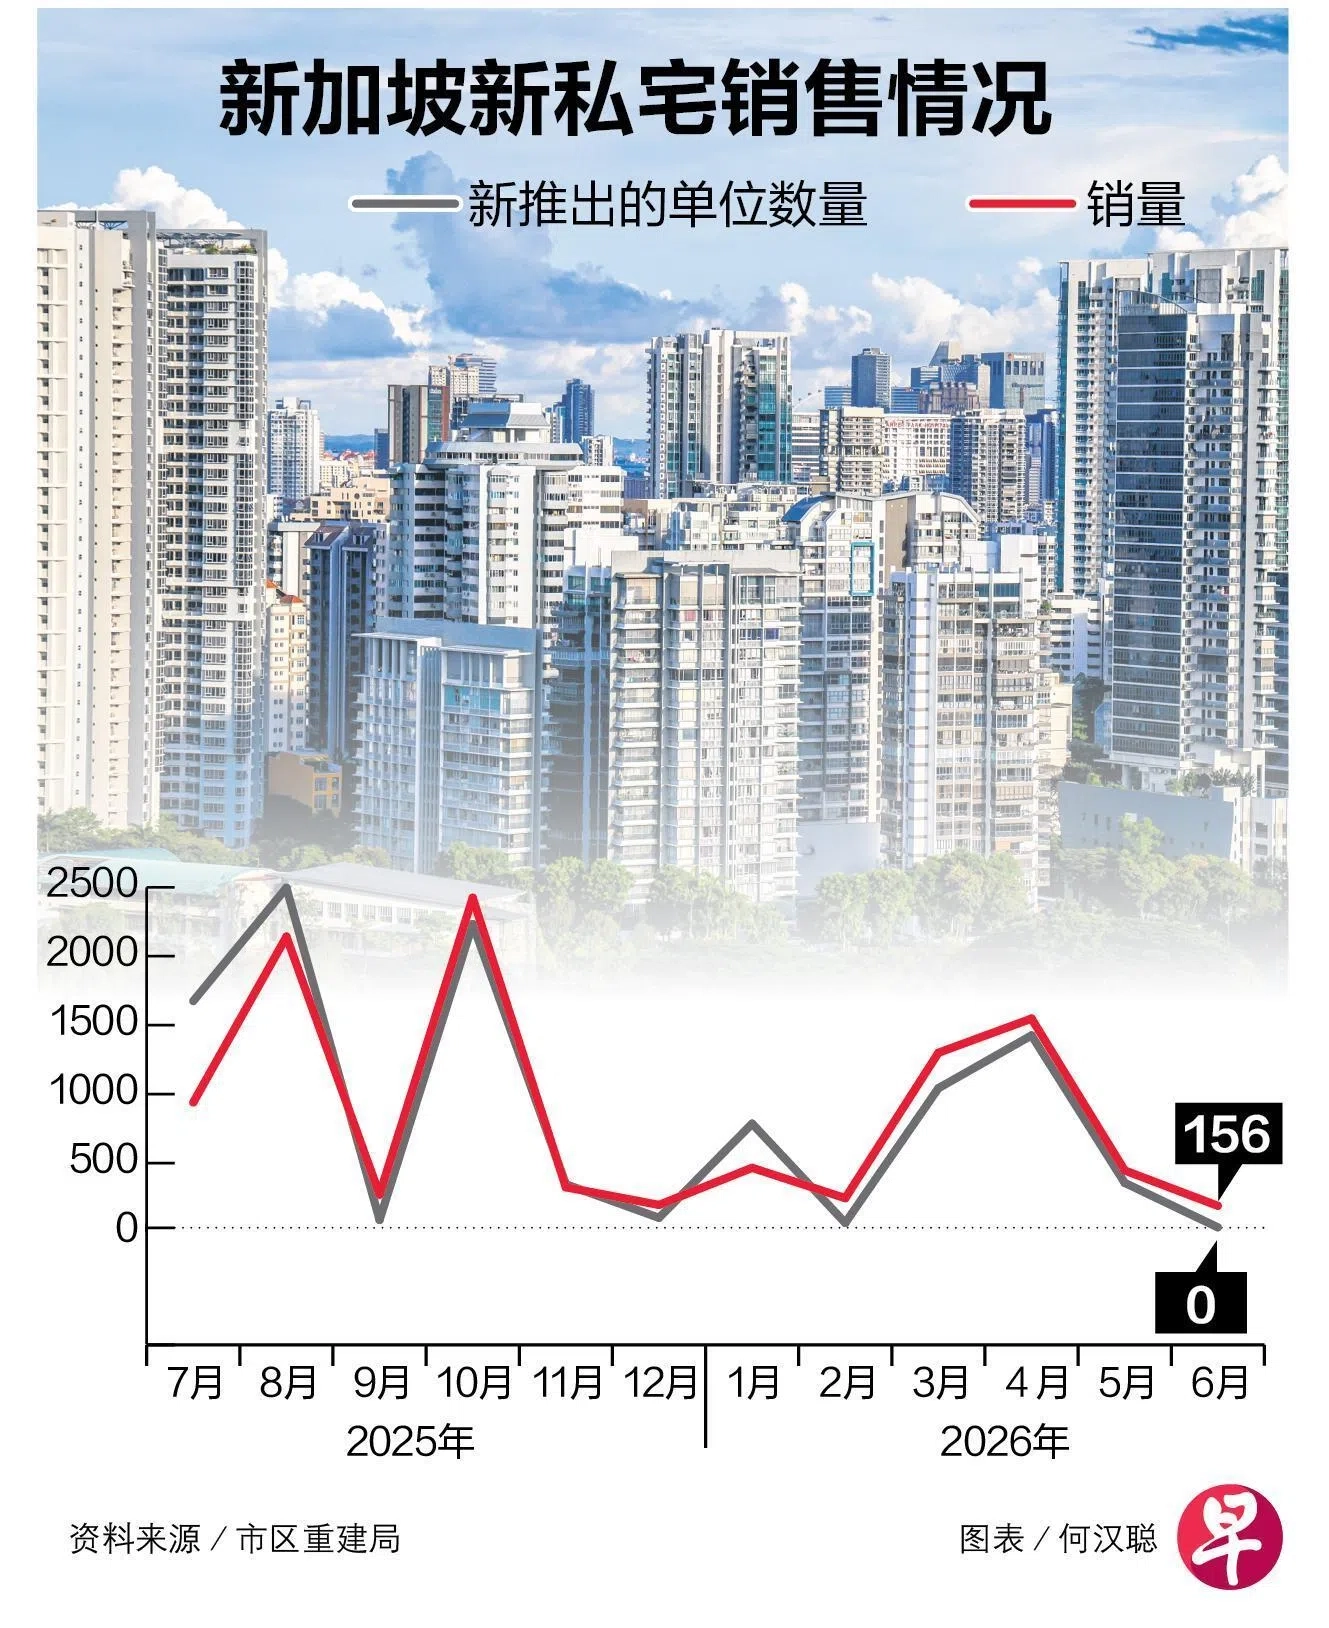
In comparison, 357 new units were officially launched in May.
As Singapore's primary market relies heavily on launch momentum to drive transaction volumes, sales naturally softened in the absence of fresh supply.
Sales Declined Across All Three Market Segments
Across the different market segments, sales in all three regions recorded noticeable declines in June.
The Rest of Central Region (RCR), which represents the city-fringe mid-tier segment, remained the top performer with 84 units sold, though this marked a steep 74.9% decline month-on-month (MoM).
The Outside Central Region (OCR) recorded 57 transactions, down 37.4% from May.
Meanwhile, the prime Core Central Region (CCR) logged 15 transactions, slipping 31.8% MoM.
In the Executive Condominium (EC) segment, 28 units were transacted during the month.
First-Half Performance Remains Resilient Overall
Despite the pronounced slowdown in June, the market's performance remains relatively healthy when viewed across the wider first half of the year.
For the first half of 2026 (1H 2026), developers moved a cumulative total of 4,164 new private homes, representing a modest YoY decline of just 9.2%.
Although escalating Middle East tensions in February temporarily injected uncertainty into the global economy, sales rebounded robustly between March and April on the back of several major project launches, reflecting resilient underlying homebuyer demand.
Luxury Segment Stages a Strong Comeback
Beyond steady activity in the mass market, the prime luxury segment has also staged a marked recovery this year.
Data reveals that in 1H 2026, 60 luxury homes priced between S$5 million and S$10 million changed hands, representing a staggering 185.7% surge compared to the same period last year.
Amid prevailing global macroeconomic and geopolitical uncertainties, an increasing number of high-net-worth individuals (HNWIs) continue to allocate capital to Singapore's property market, drawn by its political stability and economic resilience.
Which Projects Were the Top Sellers in June?
Despite the overall dip in transaction volumes, several popular projects continued to see steady absorption.
The top-selling project was:
Hudson Place Residences
12 units sold
Median price: S$2,577 psf
Other top performers included:
The Chuan Park
11 units sold
Median price: S$2,631 psf
The Continuum
11 units sold
Median price: S$2,789 psf
Union Square Residences
11 units sold
Median price: S$2,762 psf
Why Are Analysts Generally Bullish on July?
Market watchers widely view June's low transaction volume as a transient blip.
With developers keen to front-load launches before the Lunar Seventh Month (Hungry Ghost Festival, running from 13 August to 11 September 2026), several new projects are slated to hit the market in July, which should spur a sharp recovery in sales volume.
Among the most anticipated upcoming launches are:
Lentor Gardens Residences
Dunearn House
As these major developments debut, they are expected to inject fresh momentum into market transactions.
Full-Year Sales Projections Remain Optimistic
Market research agencies maintain a positive outlook on the overall private residential market for 2026.
Key catalysts include:
A pipeline of attractive new project launches;
Stable employment conditions and resilient household balance sheets;
Relatively steady mortgage interest rates.
Conclusion: June a Brief Lull; Second-Half Pipeline Set to Reignite Market
While June logged the first "zero new launch" month in nearly two decades, triggering a 65% plunge in private new home sales, this represents a launch hiatus driven by strategic developer timing rather than any fundamental deterioration in homebuyer demand.
With flagship developments like Lentor Gardens Residences and Dunearn House entering the market, and developers eager to launch before the Hungry Ghost Month, market activity is well-positioned for a swift rebound in July.
For prospective homebuyers and investors, the second half of the year will not only provide a broader selection of choices, but also an opportune window to assess price trends and market sentiment.