News · New Launches
Core Central Region Luxury Home Launches in 2025 Set to Test Market Resilience

In 2025, Singapore’s Core Central Region (CCR) is expected to see a wave of high-end residential launches, serving as a critical litmus test for demand and price resilience in the luxury property market. As more prime developments enter the market, buyers will enjoy a broader selection, while developers will face keen market competition.
The residential property market in 2025 is poised for exciting developments. Data indicates that over 30 new projects are expected to be launched, including three Executive Condominiums (ECs), yielding a combined total of around 14,000 new units. This marks a significant increase compared to 2024, which saw 24 project launches (including two ECs) and over 7,300 units.
These new launches will be evenly distributed across Singapore’s three primary sub-markets: the Core Central Region (CCR), the Rest of Central Region (RCR), and the Outside Central Region (OCR), providing a diverse spectrum of options for home seekers and investors alike.
With a robust launch pipeline spanning every region, the 2025 property market will offer multifaceted opportunities to cater to the differing needs and preferences of buyers and investors.
Surge in CCR Project Launches
Buoyed by improving market sentiment, 2025 is expected to see a greater number of projects launched in the Core Central Region (CCR), including developments that were deferred following the property cooling measures rolled out in April 2023. These measures notably doubled the Additional Buyer’s Stamp Duty (ABSD) for foreign buyers to a steep 60%.
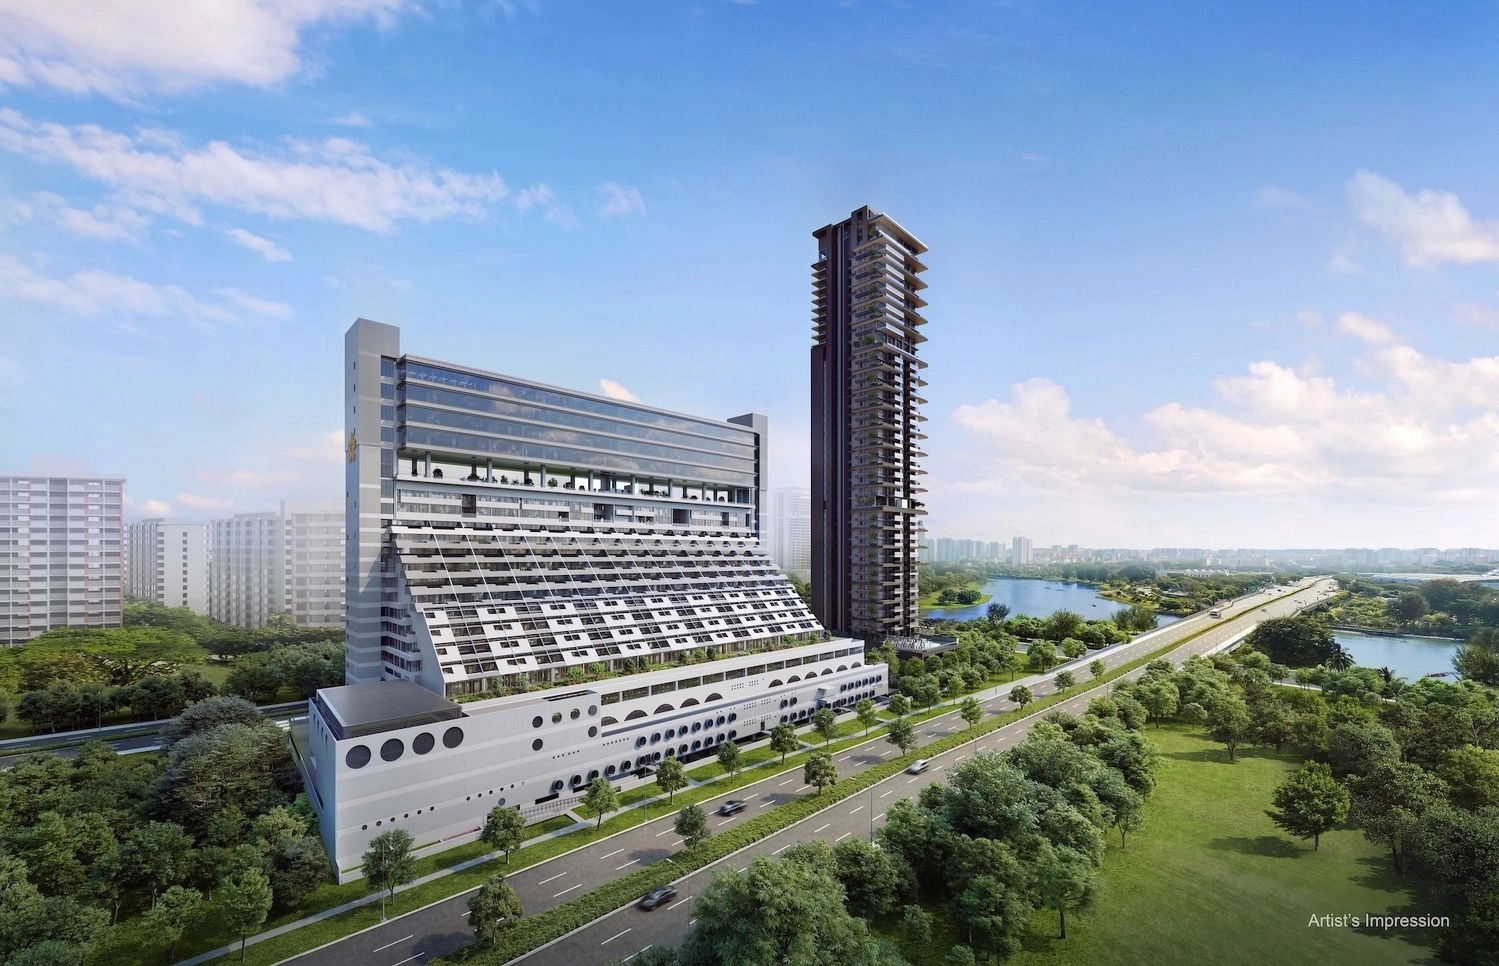
New Launch: Aurea
One of the highlight projects of 1Q2025 is Aurea on Beach Road. Comprising 188 units across a 45-storey residential tower, it forms part of the Golden Mile Singapore integrated development, jointly undertaken by Far East Organization and Perennial Holdings. Aurea will be seamlessly integrated with the conserved former Golden Mile Complex, which was acquired via collective sale in April 2022 for S$700 million. This marked the very first en bloc acquisition involving a conserved building and drew significant market attention.
Aurea is well-poised to benefit from the ongoing urban rejuvenation along Beach Road and the Ophir-Rochor Corridor, as well as the nearby Kallang Alive sports and lifestyle precinct, substantially enhancing its appeal to prospective purchasers.

IOI Properties Group Launches W Residences Singapore – Marina View
W Residences Singapore – Marina View is another marquee project slated for launch in 1Q2025. Developed by IOI Properties Group, this ultra-luxurious 51-storey mixed-use development comprises 683 residential units alongside the 350-key W Singapore – Marina View hotel.
This marks the first hotel-branded luxury residential launch since Pullman Residences Newton in 2019. Key selling points include its prime address within the Downtown Core, its proximity to Shenton Way MRT station on the Thomson-East Coast Line (TEL), and the abundant retail and dining amenities nearby.
Prime Residential Enclaves in Holland and Orchard
Another highly anticipated development is the 680-unit private condominium at Holland Drive, jointly developed by CapitaLand, UOL Group, Singapore Land Group (SingLand), and Kheng Leong Co. The project sits on a Government Land Sales (GLS) site secured in May 2024 for S$805.39 million, translating to approximately S$1,285 per square foot per plot ratio (psf ppr).

Holland Village and Orchard Boulevard: Luxury Residential Highlights for 2025
The 680-unit private condo at Holland Drive enjoys a stellar location just a short stroll from Holland Village MRT station on the Circle Line. The development also sits adjacent to One Holland Village, the newly completed mixed-use destination by Far East Organization, Sino Group, and Sekisui House.
Residents will enjoy direct access to the rich array of dining, entertainment, and retail offerings in Holland Village, a vibrant convenience that significantly elevates the project’s appeal among prospective homebuyers.
Strong Appeal of Orchard Boulevard Luxury Residences
Another standout project on the horizon is the 280-unit luxury condominium along Orchard Boulevard, jointly developed by UOL Group and SingLand. Directly fronting Orchard Boulevard MRT station on the TEL, the project occupies an exceptional location within easy reach of Tanglin Mall, the Singapore Botanic Gardens, Orchard Road, and Dempsey Hill.
The developers secured the GLS site in February 2024 with a winning bid of S$428.28 million (S$1,617 psf ppr). This was some 32% lower than the Cuscaden Road GLS plot awarded six years earlier at S$2,377 psf ppr, which was subsequently developed into the 192-unit Cuscaden Reserve.
Market Performance: Price Adjustments Drive Sales Velocity
Following a price recalibration in March 2024, Cuscaden Reserve has achieved an 83% take-up rate. The 147 units sold this year went for an average of S$3,071 psf, representing a notable adjustment from the average of S$3,625 psf achieved across the 12 units sold during its initial launch in 2019.
Outlook: Prime Projects to Watch in 2025
Backed by its prime location, comprehensive amenities, and competitive land pricing, the Orchard Boulevard development stands out as one of the most compelling luxury residential launches to monitor in 2025.

Diverse Choices — From River Valley to Robertson Quay
The Core Central Region (CCR) will also welcome a 348-unit mixed-use development along Unity Street at Robertson Quay, jointly developed by Frasers Property and Sekisui House. The project redevelops the former Robertson Walk and Fraser Place Robertson into an integrated enclave blending residential, dining, and lifestyle amenities, with targeted completion in 2028.
Another closely watched CCR launch is Newport Residences, a 246-unit freehold residential development by CDL. Forming part of the mixed-use Newport Plaza development on the site of the former Fuji Xerox Towers, Newport Residences is slated to play an integral role in the urban regeneration of the Central Business District (CBD).
River Green: A Highly Anticipated 2025 Launch
River Green, a 400-unit residential project developed by Wing Tai Holdings, ranks among the most closely followed new launches in 2025. The River Valley Green site was awarded via GLS in June for S$464 million (S$1,325 psf ppr).
Situated right next to Great World MRT station (Thomson-East Coast Line), and within walking distance of Great World City and River Valley Primary School, the development's prime location serves as a major drawcard for buyers.

The Collective at One Sophia and Other Launches to Spark Homebuying Wave in 2025
Following its private sales in November, The Collective at One Sophia is slated to commence public previews on 4–5 January 2025, with official sales scheduled for 18 January. Jointly developed by SingHaiyi and Ultra Infinity, this District 9 mixed-use project features 367 residential units. The site formerly housed Peace Centre and Peace Mansion, which the joint venture acquired en bloc in December 2021 for S$650 million.
These upcoming launches will cater to a wide spectrum of owner-occupiers and investors. The varied selections in the CCR will reignite buyer interest in the prime segment. Meanwhile, a plentiful pipeline across the RCR and OCR will continue to attract upgraders and investors, with many projects strategically located near MRT stations and established amenities.
RCR and OCR Projects Ready to Kick Off 2025
The new year will open with two highly anticipated developments: The Orie in Toa Payoh and Bagnall Haus along Upper East Coast Road, both opening for preview over the weekend of 4–5 January.

The Orie and Bagnall Haus: Two Spotlight Launches Early in 2025
Located at the junction of Lorong 1 and Lorong 4 Toa Payoh, The Orie comprises two 40-storey residential towers with a total of 777 units. It offers diverse configurations ranging from one-bedroom plus study to five-bedroom apartments, with unit sizes spanning 517 to 1,453 sq ft.
The developers expressed great enthusiasm about ushering in the new year with the launch of The Orie. Not only does it represent the first private residential launch in Toa Payoh in eight years, but it will also inject fresh vibrancy into this highly sought-after city-fringe estate.
Bagnall Haus: A Fresh Highlight on the East Coast
Another spotlight project is Bagnall Haus along Upper East Coast Road, a 113-unit development by Roxy-Pacific Holdings. The project is situated close to the upcoming Sungei Bedok MRT station, which will serve as an interchange between the Thomson-East Coast Line (TEL) and Downtown Line (DTL) upon completion in 2028.
Bagnall Haus is a redevelopment of the former Bagnall Court, which Roxy-Pacific acquired en bloc in February 2023 for S$115.28 million (S$1,106 psf ppr).
This marks the first new residential launch in the District 16 East Coast neighbourhood since Eastwood Regency in early 2010. Furthermore, with its close proximity to Bayshore—a precinct slated to become a major residential growth node—Bagnall Haus carries strong capital appreciation potential.
Addressing prolonged supply gaps in Toa Payoh and the East Coast respectively, both developments boast premier locations and significant growth upside, setting the stage for strong buying momentum in early 2025.
Multiple Launches Herald a Dynamic 1Q2025
Elta: A New Focal Point in Clementi
Located at Clementi Avenue 1, Elta is a 501-unit residential project jointly developed by CSC Land Group and MCL Land, slated for launch in 1Q2025. The development is likely to see robust demand, as previous launches in the immediate vicinity—The Clement Canopy (505 units, launched in 2017) and Clavon (640 units, launched in 2020)—are completely sold out.
Its proximity to top-tier educational institutions adds substantial allure, with Pei Tong Primary School, Nan Hua High School, NUS High School of Mathematics and Science, and the National University of Singapore (NUS) all nearby.
Lentor Central Residences: A New Benchmark for Lentor
Lentor Central Residences, jointly developed by GuocoLand, Hong Leong Holdings, and CSC Land Group, is also set to debut in 1Q2025. Comprising 477 residential units in the Lentor Hills Estate, the project marks GuocoLand’s continued placemaking efforts in this expanding private residential enclave. As the developer’s fourth residential undertaking in Lentor, it underscores strong confidence in the precinct’s long-term growth trajectory.
Catering to a variety of buyer profiles, these two projects will further enrich the 1Q2025 pipeline, offering home seekers and investors prime new choices.

Mega Developments of 2025: Parktown Residences Takes Centre Stage
1Q2025 will also welcome two mega residential developments. Among them, Parktown Residences is the largest, boasting 1,193 residential units as part of an integrated development along Tampines Avenue 11.
Jointly developed by CapitaLand, UOL, and SingLand, the project integrates private residences, retail mall spaces, a hawker centre, a community club, and a transport hub comprising a bus interchange and direct connection to the future Tampines North MRT station on the Cross Island Line (CRL).
Parktown Residences is poised to capture deep upgrader demand from surrounding mature estates such as Tampines, Simei, and Pasir Ris. By combining comprehensive lifestyle amenities with seamless transport connectivity, this integrated mega-hub stands out as one of the year’s most eagerly awaited developments.

1Q2025 Highlights: Mega Residential Launches at Marina Gardens Lane and Zion Road
Marina Gardens Lane: Waterfront Luxury by Gardens by the Bay
Another landmark project to look out for is the 937-unit residential development at Marina Gardens Lane, expected to debut in 1Q2025. The project is spearheaded by Kingsford Group alongside joint venture partners Obsidian Development and Polarix Cultural and Science Park Investment.
Kingsford Group has demonstrated strong market traction recently, following the blockbuster launch of The Chuan Park in 2024 and the complete sell-out of Normanton Park.
A Busy February: Cluster of Launches Post-Chinese New Year
February 2025—following the Chinese New Year festivities—is shaping up to be a busy month, with three launches slated for the same window: Lentor Central Residences, Elta, and the Aurelle of Tampines EC. However, a repeat of November 2024's simultaneous multi-project launch rush is unlikely, with much hinging on whether developers secure the necessary approvals and sale licences from authorities in time.
Prime RCR Contenders: Zion Road and Margaret Drive
Zion Road Parcel A: Pioneering Long-Stay Serviced Apartments
The 2025 launch roster features two significant projects along Zion Road. The first is Zion Road Parcel A, comprising 1,170 residential units and approximately 300 long-stay serviced apartments. The site was awarded in April 2024 to a CDL and Mitsui Fudosan joint venture for S$1.107 billion (S$1,202 psf ppr). This marks the first GLS site to incorporate long-stay serviced apartments, which require a minimum stay duration of three months.
Zion Road Parcel B: Allgreen’s Prime Riverfront Project
Adjacent to Parcel A sits Zion Road Parcel B, acquired by Allgreen Properties in July 2024 for S$730.09 million (S$1,304 psf ppr). Allgreen plans to develop a 610-unit residential project on the site, with a launch targeted for later in 2025.
These developments not only cater to pent-up demand for prime city-fringe living in the RCR, but also introduce fresh, innovative housing typologies to the market.

Margaret Drive: Prime City-Fringe Address Draws Upgrader Demand
A brand-new 460-unit private residential project along Margaret Drive is expected to hit the market in the second half of 2025. The GLS site was secured for S$497 million (S$1,154 psf ppr) by a consortium comprising GuocoLand, Intrepid Investments (a wholly owned subsidiary of Hong Leong Holdings), and Hong Realty (under Hong Leong Group).
Location Merits and Latent Demand
Thanks to its prime Queenstown city-fringe location, the project is anticipated to command strong buyer interest. It is located close to Queenstown MRT station, sits within 1 km of three schools, and enjoys immediate access to rich retail, dining, and lifestyle amenities.
Substantial upgrader demand from surrounding mature HDB clusters in Dawson and Queenstown is expected to provide robust support for the development.
Location and Project Attributes Remain Paramount
Location and product attributes remain front and centre for buyers making purchasing decisions. Thoughtfully designed, quality developments close to MRT stations, daily conveniences, and reputable schools consistently generate compelling interest.
Furthermore, residential estates that have seen no new launches for years often witness strong pent-up demand. With its enviable location and lifestyle conveniences, the Margaret Drive project is well positioned to become one of the premier focal points of 2025.

Price Trends and Market Dynamics
New home sales volume in 2025 is forecast to range between 7,000 and 9,000 units, up from around 6,500 units in 2024 and aligning closely with the 10-year historical annual average of 8,853 units.
Private home prices are projected to grow by 3% to 4% in 2025, compared to an estimated full-year growth of around 3% in 2024.
Regional Disparities in Price Growth
From 1Q2020 to 3Q2024, non-landed private home prices in the CCR grew by just 15.1%, whereas prices in the RCR and OCR surged by 42.2% and 40.6% respectively.
Underlying Reasons for Moderate CCR Growth
The more subdued price appreciation in the CCR is largely attributable to successive rounds of property cooling measures, which primarily impacted property investors and foreign buyers—the core target demographic of the prime CCR market.
Price movement in 2025 will continue to be guided by prevailing policy settings and localized demand, yet fundamentals remain solid, with overall transaction volume expected to normalize back toward historical averages.
Market Outlook for 2025
Domestic buyer demand in the RCR and OCR is projected to stay resilient. Owing to rising land and construction costs, price increases have been comparatively steeper in these suburban and city-fringe segments.
As the price premium between the CCR and the RCR/OCR continues to compress, attractive value propositions are emerging in the prime luxury segment—a trend likely to persist through 2025.
Nevertheless, buyers remain prudent and discerning. Strong sales momentum observed in November was not uniformly spread across all launches. For instance, higher-quantum prime projects such as The Collective at One Sophia and Union Square Residences registered more measured take-up rates.
In contrast, suburban and city-fringe developments such as The Chuan Park, Emerald of Katong, and Nava Grove experienced robust demand, largely underpinned by standout project attributes and accessible absolute price quantums that aligned closely with the budgets of mainstream buyers.