News
CCR-RCR Price Gap Narrows: Why High-End Buyers Are Betting on the Core Central Region Again
Singapore’s Ultra-Luxury Property Market Rebounds in 2025 as High-End Buyers Return
In 2025, Singapore’s luxury condominium market regained strong momentum, with several blockbuster transactions redefining market benchmarks. The year recorded at least 13 transactions exceeding S$5,000 per square foot (psf) and 16 deals crossing the S$20 million mark, signalling a notable resurgence in demand for prime luxury properties.
According to data, 383 luxury condominium units were transacted in Singapore over the first 11 months of 2025, with total transaction value surpassing S$3 billion at an average price of around $2,960 psf.
Compared to 274 units totalling S$1.998 billion in 2024, overall transaction value surged by 50.6% year-on-year.
Under this definition, luxury condominiums primarily refer to premier residential developments located in the Core Central Region (CCR) priced from S$5 million upwards, characterised by exceptional positioning and top-tier specifications.
21 Anderson: The Standout Luxury Star of 2025
Among all top-tier luxury property transactions in 2025, 21 Anderson was undoubtedly the biggest winner.
The development captured 11 spots among the top 15 highest-value transactions and 7 spots among the top 15 highest psf prices. Since its launch in April, 12 of its 18 exclusive units have been sold, including two penthouse duplexes transacted at S$52.25 million each (around $4,999 psf)—tying for the highest condo transaction value of 2025.

The key to the project’s success lies in how precisely it addressed an acute void in the current market.
There was virtually no new supply of brand-new, freehold, large-format luxury homes, and 21 Anderson arrived at precisely the right moment.
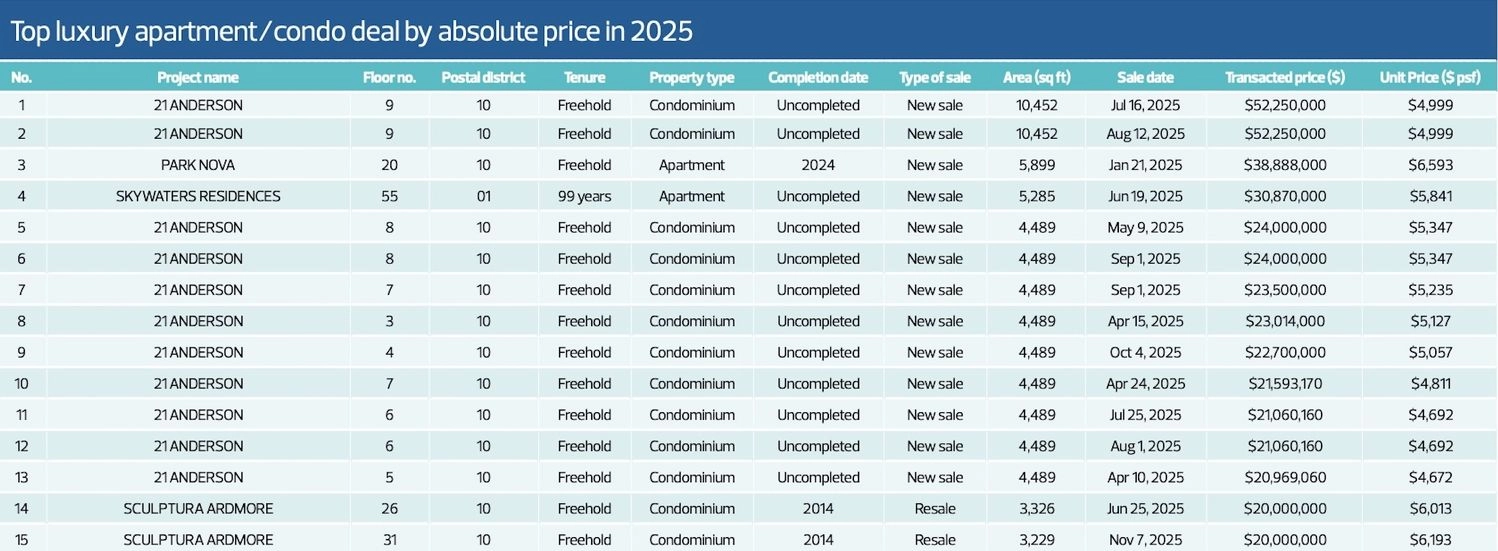
Situated in the prestigious Ardmore–Anderson enclave of District 10, the penthouses boast expansive floor areas of up to 10,452 sq ft, featuring amenities such as walk-in wine cellars, private rooftop swimming pools, jacuzzis, and unblocked city views—firmly tailored for ultra-high-net-worth individuals (UHNWIs).
Notably, only three of the buyers were Singapore citizens, with the remainder predominantly being Permanent Residents (PRs), primarily of Chinese background.
The "Brand Trust Effect" Behind Luxury Closings
Beyond the product itself, the developer’s longstanding pedigree has also been a crucial catalyst.
Kheng Leong has spent decades cultivating the prime residential segment. Its portfolio includes 32 Gilstead, MeyerHouse, 15 Holland Hill, and Nassim Park Residences, all renowned for their generous proportions, low-density exclusivity, and exceptional craft.
Taking 32 Gilstead as an example, since its debut in 2024, its average transaction price has reached $3,493 psf, with the latest deal setting a new high of $3,592 psf—further demonstrating how discerning luxury buyers place immense value on brand and quality.
Record-Breaking PSF Prices: Luxury Real Estate Transcends Tenure
The year's highest psf transaction emerged from Park Nova, where a penthouse changed hands at $6,593 psf to set a new annual benchmark.

Even more symbolic is how 99-year leasehold branded residences have scaled new heights.
Skywaters Residences in the CBD recorded a sale within its Aman branded residences at $6,501 psf in October, illustrating that luxury buyers’ appreciation for "brand + hospitality + scarcity" is gradually superseding traditional tenure preferences.

Resale Luxury Remains Resilient: Heritage Prime Enclaves Continue to Attract Capital
Alongside new launches, established luxury residences have delivered an equally stellar showing.

Trophy developments such as The Marq on Paterson Hill and Sculptura Ardmore have logged resale transactions exceeding $6,000 psf, with purchasers spanning Singaporeans, PRs, and HNWIs from Europe and North America.

These developments share distinct hallmarks:
Freehold tenure + mature prime location + proven architectural excellence, serving as formidable "anchors of capital preservation" amid market fluctuations.
Narrowing Price Gap Between CCR and RCR Restores Allure to Prime Districts
Studies point out that the luxury rebound in 2025 was also driven by a noticeable narrowing of the price gap between new launches in the CCR and the Rest of Central Region (RCR).
Some new CCR launches command only a 5% to 7% premium over RCR developments, a stark contrast to the roughly 25% premium observed in the first half of 2024.
With the price gap compressed, more buyers are opting to step straight into the prime core, laying a solid foundation for upcoming CCR launches in 2026.
Conclusion: High-End Buyers Return as Luxury Enters a Structural Recovery
Singapore’s luxury property market in 2025 is not driven by irrational exuberance, but rather represents a highly calculated, structural recovery:
Ultra-prime transactions are concentrated in scarce, premier developments
Brand pedigree, product excellence, and prime location have re-emerged as the definitive benchmarks
The long-term value of the CCR is being re-rated
For high-net-worth buyers and long-term investors, luxury homes represent far more than mere living spaces—they are an enduring embodiment of capital preservation, prestige, and timeless value.