News
[Annual Review] Did New Launches Sell Like Crazy? A Look Back at 2025's New Projects
2025 New Launch Sales Leaderboard Reveals: Singapore Residential Market Enters a Broad-Based Recovery
In 2025, Singapore's new private home market delivered results that substantially beat expectations.
Among the top 15 best-selling new launches of the year, as many as nine projects achieved a take-up rate exceeding 90%. This clearly illustrates that the market's recovery was not reliant on just a handful of "blockbusters", but was underpinned by broader, more balanced genuine homebuyer demand.
Notably, Skye at Holland along Holland Road and LyndenWoods on Science Park Drive both surpassed a 99% sales rate. Meanwhile, Lentor Central Residences has sold out completely.

Spanning diverse regions and market positioning, these projects simultaneously achieved high absorption rates, demonstrating the residential market's remarkable resilience and underlying strength amid rising global economic uncertainties and geopolitical headwinds in 2025.
New Home Sales Hit Multi-Year Highs as Full-Year Momentum Strengthens Substantially
According to real estate market outlook reports, developers sold approximately 10,620 new private residential units (excluding Executive Condominiums) in the first 11 months of 2025.
This figure is not only significantly higher than the annual tally of roughly 6,400 to 8,000 units recorded between 2022 and 2024, but also signals that new home transaction momentum has returned to multi-year highs.
The top three best-selling projects alone sold a combined 2,748 units, accounting for about a quarter of the year's total transaction volume.
Top 3 Best-Selling New Launches in 2025
Leading the pack was ParkTown Residences in Tampines North. It was the only mega-development with over 1,000 units launched in 2025, offering a total of 1,193 homes. The 99-year leasehold integrated development brings together residences, a retail mall, and a transport hub, with direct links to Tampines North MRT station on the Cross Island Line and a bus interchange.

The project moved 87% of its units during its launch weekend in February and had sold around 93% by mid-December, making it the most emblematic best-seller of the year.
Coming in second was Springleaf Residence, developed by GuocoLand. Comprising 941 units, the development has sold around 96% of its units to date. Connected to Springleaf MRT station on the Thomson-East Coast Line and situated right next to the protected Springleaf Forest, its distinct natural surroundings drew a strong pool of owner-occupiers and upgraders.

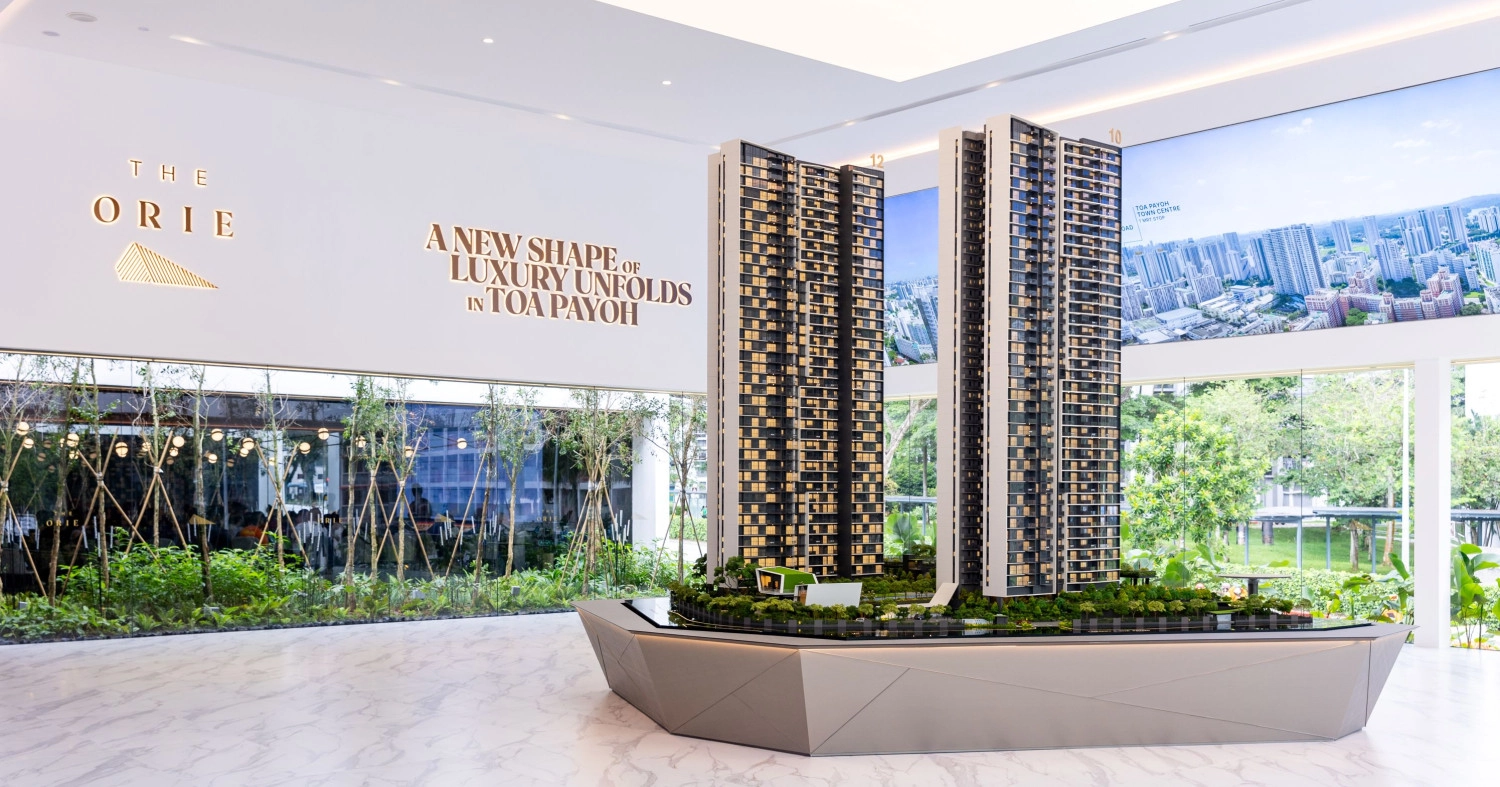
Taking third place was The Orie in Toa Payoh. As the mature estate’s first new private residential launch in over a decade, it was jointly developed by CDL, Frasers Property, and Sekisui House. The project achieved an 86% take-up rate upon its launch in January and has since reached a 94% sales rate, underscoring the sustained unlocking of upgrading demand across mature towns in 2025.
Strong Sales Volumes, Yet Price Growth Remains Measured
Despite robust new launch sales, overall private home price growth has remained relatively measured.
In the first nine months of 2025, the URA Private Residential Property Price Index rose by just 2.7%. In fact, private home price growth has moderated for the third consecutive year since 2022, following a 3.9% gain in 2024.
Full-year projections for 2025 remain in the 3% to 4% range. This indicates that the rebound in transaction volume in 2025 was largely driven by genuine demand being unlocked, rather than price escalation.
From a supply perspective, 2025 was also a year of revitalisation for the Core Central Region (CCR).

Research data indicates that approximately 23% of new launch units were located in the CCR, marking the largest influx of new supply into the prime segment since 2021. Launches across the year spanned boutique freehold luxury residences, landed properties, branded residences, and mid-to-large prime developments, offering prime-district buyers a richer selection of choices and rekindling market interest in the CCR.
EC Market Equally Robust, Driven by Concentrated First-Timer and Upgrader Demand
Beyond private residential properties, Singapore’s Executive Condominium (EC) segment also put up a stellar performance in 2025. Only two EC projects were launched throughout the entire year, yet both registered exceptionally high take-up rates.
Aurelle of Tampines in Tampines cleared around 90% of its units over its launch weekend in March and was fully sold within a month.

Otto Place in Tengah debuted in July, finding buyers for over half of its units on launch day, and is now virtually sold out.

This reflects that within the relatively accessible price bracket, purchasing power among upgraders and first-time buyers remains exceptionally resilient.
Why Did 2025 New Launches Perform So Strongly?
What drove such stellar performance in the 2025 new launch market? Sensibly priced new supply, pent-up homebuying demand, softening interest rates, and an improved local economic outlook were all key catalysts.
Following US Federal Reserve rate cuts, local mortgage rates retreated below 2%, substantially easing home financing burdens. Concurrently, Singapore household wealth has grown steadily since 2023; by the second quarter of 2025, cash and deposits held by households had expanded considerably, providing a solid liquidity buffer for the property market.
All in all, Singapore's residential property market in 2025 was not merely experiencing a simple cyclical rebound, but exhibiting structural resilience amid multiple headwinds. Across suburban launches, prime CCR developments, and executive condominiums, the depth and velocity of transactions prove that housing demand remains intact—simply waiting for the right product, pricing, and timing. This momentum lays a remarkably sturdy foundation for the residential market heading into 2026.