News
What Is the Private Residential Market Outlook? Looking Ahead to Upcoming New Condo Launches in 2024
In 2023, the Singapore property market was fraught with uncertainties—geopolitical tensions, slowing global economic growth, high living costs, inflation, and rising interest rates. These came on top of the property cooling measures introduced in April. Adding further unease to the market was the multi-billion-dollar money laundering case involving luxury properties, cars, cash, and other assets valued at over $2.8 billion.
Many of these uncertainties are likely to persist into 2024. Nevertheless, market sentiment has improved recently amidst reports of a pick-up in manufacturing activity and a rebound in business confidence.
Located in the Jurong Lake District, the 368-unit, 99-year leasehold J'den achieved stellar sales, moving 88% of its units on launch day at an average price of $2,451 psf. Meanwhile, the 180-unit, freehold Watten House in prime District 11 also lifted market sentiment by selling 57% of its units. In Lentor Hills, the 474-unit, 99-year leasehold Hillock Green sold 130 units (28%) at an average price of $2,108 psf.
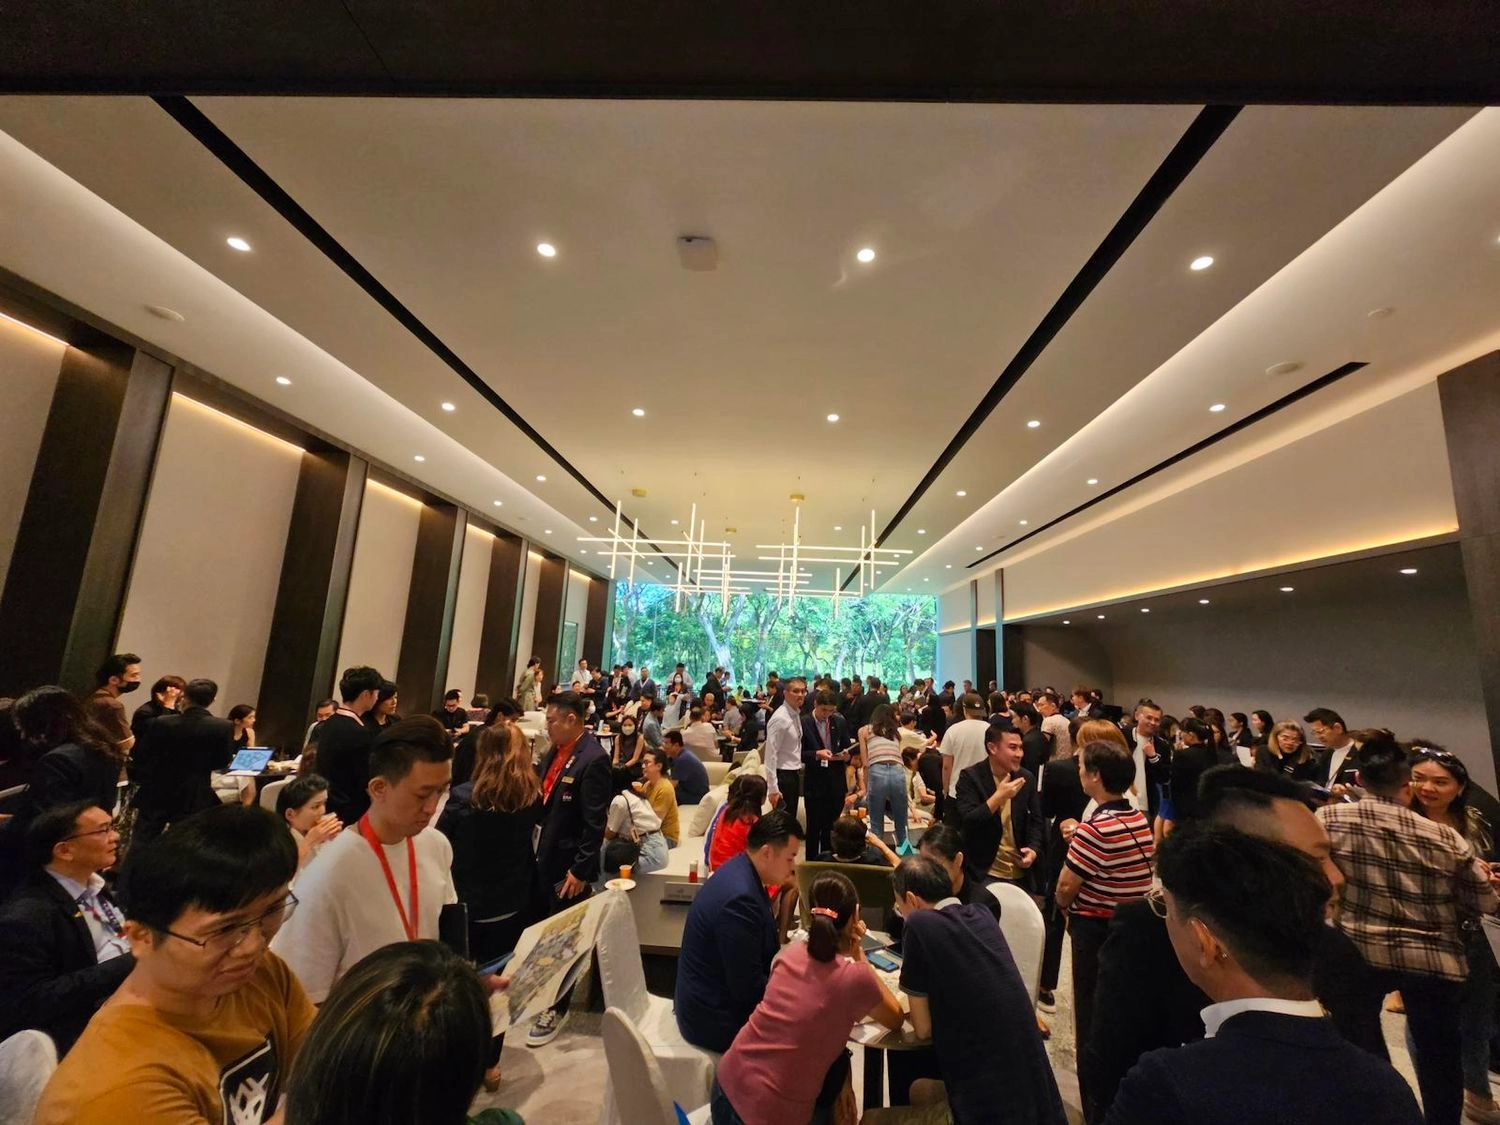
With the launches of J'den, Hillock Green, and Watten House, around 7,000 new private homes are expected to be sold this year.
Despite prevailing market headwinds, the median price for new home sales in 2023 reached $2,445 psf, up 15.5% year-on-year from $2,117 psf the previous year. This growth can be attributed to a higher proportion of new project launches in the Rest of Central Region (RCR) and Core Central Region (CCR) over the course of the year.

Home Prices Expected to Rise by Up to 6%
Property prices are projected to grow by 5% to 6% this year. Developers' bids in the 2023 Government Land Sales (GLS) tenders indicate steady, albeit more moderate, price growth for new homes in 2024. Forecasts suggest prices could climb by around 6% by the end of 2024.
New home sales next year are estimated at 7,000 to 8,000 units. The private residential market is showing clear signs of price stabilisation.

Widening Price Gap Between New Launches and Resale Properties
The widening price gap between new launches and resale homes has prompted some buyers to pivot towards the resale market. Newly completed homes have taken centre stage and are increasingly sought-after by homebuyers due to their pristine condition and move-in-ready status.
Reports indicate that approximately 19,050 private residential units (excluding ECs) were completed or obtained their Temporary Occupation Permit (TOP) this year. This figure is projected to drop significantly to 9,875 units in 2024.
Given the wide array of options across both the new launch and resale markets, most homebuyers are spoilt for choice.
As at the end of November, resale transactions stood at 10,098 units—a 28% decline from the 14,026 resale transactions recorded in 2022. By the fourth quarter of 2023, the median price gap between new launches and resale condominiums approached nearly 50%. Given that resale prices remain more accessible than new launches, resale transaction volume could rise to between 13,000 and 14,000 deals in 2024.
Over 40 New Projects Slated for Launch Next Year
Next year, more than 40 new projects comprising over 12,800 units are expected to be launched. January alone could see previews for four developments: the 172-unit freehold project The Arcady at Boon Keng; the 59-unit The Hillshore along Pasir Panjang Road; the 341-unit Hillhaven at Hillview Rise; and the 512-unit Lumina Grand EC at Bukit Batok West Avenue 5.
As the sole Executive Condominium (EC) launch in 2024, Lumina Grand will be one of the most closely watched developments of the year. Demand for freehold projects and ECs is expected to remain robust. Developments situated close to transport nodes, amenities, and reputable schools will also continue to be highly coveted by buyers.
Developed by City Developments Ltd (CDL), Lumina Grand is anticipated to perform well, as most ECs do. Lumina Grand will likely appeal to buyers who missed out on their preferred units at the nearby Altura EC. Launched in August 2023 with 360 units, Altura is already 88% sold. Lumina Grand's proximity to the upcoming Tengah Town will also attract buyers keen on moving into an up-and-coming estate.

Key Projects in the CCR
Up to 2,968 apartments are expected to launch in the CCR in 2024, marking the largest pipeline of prime-district supply since 2021.
Notable CCR launches include the 367-unit One Sophia (the former Peace Centre / Peace Mansion site) by a consortium comprising Chip Eng Seng, SingHaiyi, and KSH Holdings; the 683-unit Marina View Residences by IOI Properties Group; the 246-unit Newport Residences by CDL; and the 215-unit Skywaters Residences by Perennial Holdings and Alibaba Group.
The upcoming 790-unit residential project at Marina Gardens Lane, led by a consortium headed by Kingsford Group, is also set to draw significant buyer interest thanks to its prime location adjacent to Gardens by the Bay and the Marina Bay precinct.
Another highly anticipated CCR project is Aurea, a 186-unit development by Far East Organization, Perennial Holdings, and Sino Group on the former Golden Mile Complex site. Situated along Beach Road, this CCR project occupies a rare and prime city-fringe location.
Boutique Freehold Developments
More than ten of the projects slated for launch next year are boutique freehold developments. Boutique condos performed commendably in 2023; for instance, the 78-unit freehold Orchard Sophia has sold over 40% of its units.
Buyers looking for freehold homes in city-fringe locations can look out for Ardor Residence, as well as The Hillshore and The Arcady at Boon Keng.
Some homebuyers inherently favour boutique condo developments. Even amidst a wave of major new launches, boutique projects continue to attract steady interest, albeit at a more measured pace. Developers remain confident in the enduring appeal of freehold tenure and are content to take a more patient approach to marketing these properties.
With such a diverse pipeline of launches next year—spanning prime districts, the city fringe, and the suburbs—buyers across all segments will have plenty of compelling options to suit their property aspirations.