News
Singapore April New Private Home Sales Hit 6-Month High as OCR Launches Drive Market Rebound
April New Private Home Sales Hit Six-Month High
Driven by several major new launches in the Outside Central Region (OCR), Singapore's private residential market saw a significant rebound in April 2026.
According to data released by the URA on 15 May, developers sold a total of 1,548 new private residential units (excluding Executive Condominiums, or ECs) in April, marking the highest monthly sales volume since October 2025, when 2,424 transactions were recorded.
The strong sales rebound in April reflects continued robust buyer demand. Sales rose 19.1% month-on-month and more than doubled compared to the same period last year.
Overall Sales Dip When Factoring in ECs
However, when including ECs, total market sales actually fell by 14.9% compared to March.

This was largely because the 572-unit Rivelle Tampines EC was launched in March, which substantially lifted the sales base for that month.
With no new EC projects launched in April, the market is not expected to see any fresh EC supply for the remainder of the year until early next year.
Currently, Rivelle Tampines and Coastal Cabana remain the only two new EC projects launched in 2026.
Notably, Rivelle Tampines continued to attract a large number of second-time buyers during its second round of balloting, completely selling out last month.
Overall EC sales in April stood at 101 units, with a median price of $1,905 psf.
In the absence of new EC launches, unsold inventory continues to dwindle, leaving buyers with very limited choices for new ECs.
Two Major OCR Launches Take Centre Stage
The spotlight in April was undoubtedly on two landmark new developments.
One was Tengah Garden Residences, the first private residential project in Tengah; the other was Vela Bay, the first private residential project in the brand-new Bayshore precinct.
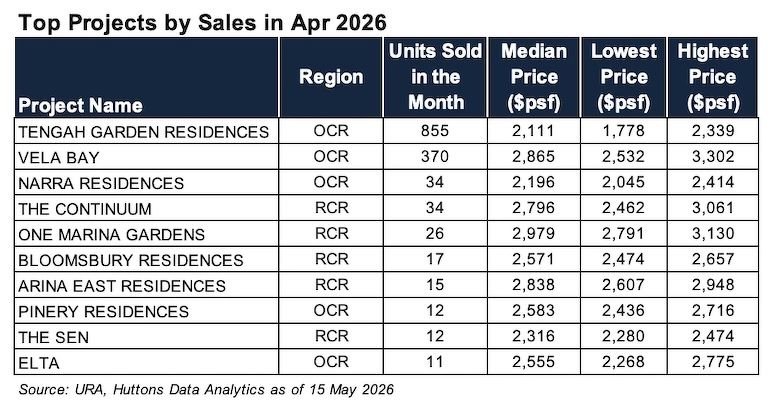
Among them, the 863-unit Tengah Garden Residences emerged as the top-selling project in April.

The project sold nearly 99% of its units over its launch weekend, met with an overwhelmingly enthusiastic market response.
With a median price of around $2,111 psf, the project offered one of the most attractive entry price points in the OCR market in 2026, successfully drawing in a large pool of buyers.
Vela Bay Sets New Benchmark Price for OCR
Meanwhile, Vela Bay delivered an equally stellar performance.
The project released 515 units and moved 370 of them, achieving a take-up rate of 71.8%.
More notably, Vela Bay set a new record median price for an OCR project at $2,865 psf.
This underscores the market's high optimism regarding the future growth potential of the new East Coast Bayshore precinct.
Together, Tengah Garden Residences and Vela Bay accounted for approximately 79% of all new home sales in April.
OCR Commands Nearly 88% of Market Transactions
Led by these two major OCR launches, the Outside Central Region dominated the market in April.
A total of 1,358 new private home transactions came from the OCR in April, accounting for a staggering 87.7% of total sales. This demonstrates that buyer demand for OCR projects remains exceptionally resilient, especially for developments offering strong location attributes and compelling value propositions.
In contrast, the Rest of Central Region (RCR) accounted for only 160 transactions, or 10.3% of the total.
The Core Central Region (CCR) recorded just 30 transactions, representing a mere 1.9%.
Evidently, market demand is currently heavily tilted towards relatively more affordable OCR developments.
RCR Market Poised to Heat Up in May
The RCR market has been notably quiet over the past few months.
Since the launch of The Sen in November 2025, the RCR has seen an absence of major new project launches for an extended period.
However, this trend may shift in May. Located at Media Circle, the 327-unit Hudson Place Residences officially launched over the weekend of 16–17 May, marking the first major RCR launch of 2026.
Market observers widely anticipate that the project could revitalise transaction activity in the RCR.
In addition, two boutique freehold developments could potentially hit the market this month: Duet @ Emily in District 9 and Verde Joo Chiat in District 15.
CCR Remains Subdued, but Super-Prime Deals Still Shine
While overall transaction volumes in the CCR remained low, the luxury segment continued to record big-ticket sales.
The best-performing CCR project in April was River Modern, which moved 11 units at a median price of $3,363 psf.
At the same time, the three most expensive new home transactions in April comprised: two units at 21 Anderson, transacted at S$22.5 million and S$21.9 million respectively; and a unit at Skywaters Residences, which changed hands for around S$12.5 million.
These high-value transactions reaffirm that demand among ultra-high-net-worth individuals for prime luxury properties in Singapore remains steadfast.
Market Outlook Stays 'Cautiously Optimistic'
Overall, developers sold 3,561 new residential units in the first four months of 2026, down 12.1% from the 4,050 units logged in the same period last year.
Nevertheless, CBRE notes that buyer demand continues to demonstrate notable resilience. Even amid heightened global macroeconomic volatility and persistent geopolitical tensions in the Middle East, demand has held up better than expected.
With fewer new launches slated for May, sales volume could see a temporary lull, but momentum is likely to pick up again as several key projects roll out in the second half of the year.
However, if tensions in the Middle East escalate further or global economic growth slows down more than anticipated, buyer hesitation may rise.
Particularly against the backdrop of inflationary pressures driven by higher energy and food costs, buyers are expected to become increasingly cautious and selective in their purchasing decisions.
Consequently, developer pricing strategies will remain a critical determinant of market success.
CBRE Forecast: Home Prices to Post Steady Gains in 2026
Looking at the full-year trajectory, CBRE projects that new private home sales in 2026 will come in between 7,500 and 8,500 units.
While this represents a moderation from the 10,815 units logged in 2025, it remains at a healthy level.
Underpinning the market are a steady pipeline of launches, healthy household balance sheets, and relatively lower mortgage rates.
On the pricing front, following a 0.9% increase in Q1 2026, CBRE expects private home prices to maintain steady growth over the course of the year, with full-year gains forecast between 2% and 4%.