News
Robust New Private Home Sales in Lentor: Driving a Revaluation of MRT Precinct Properties?
2,800 Private Homes Sold in Two Years: Is Lentor the New Success Model for Cluster Housing Development in Singapore?
With approximately 2,800 units sold in just two years, Lentor is rapidly becoming a textbook success story for private residential cluster development in Singapore.

Since the government unveiled the master plan for the Lentor precinct in 2021, this once-quiet enclave in the North has been thrust into the market spotlight, spurred by the opening of the Thomson-East Coast Line MRT station and a wave of new condo launches. To date, the overall take-up rate across the six launched projects in Lentor has reached an impressive 96%, accompanied by steady capital appreciation.
However, behind this remarkable performance lie critical realities—softening land tender prices, fluctuating buying momentum, and concerns over potential future oversupply. These insights provide vital lessons for Singapore’s next phase of urban residential planning.
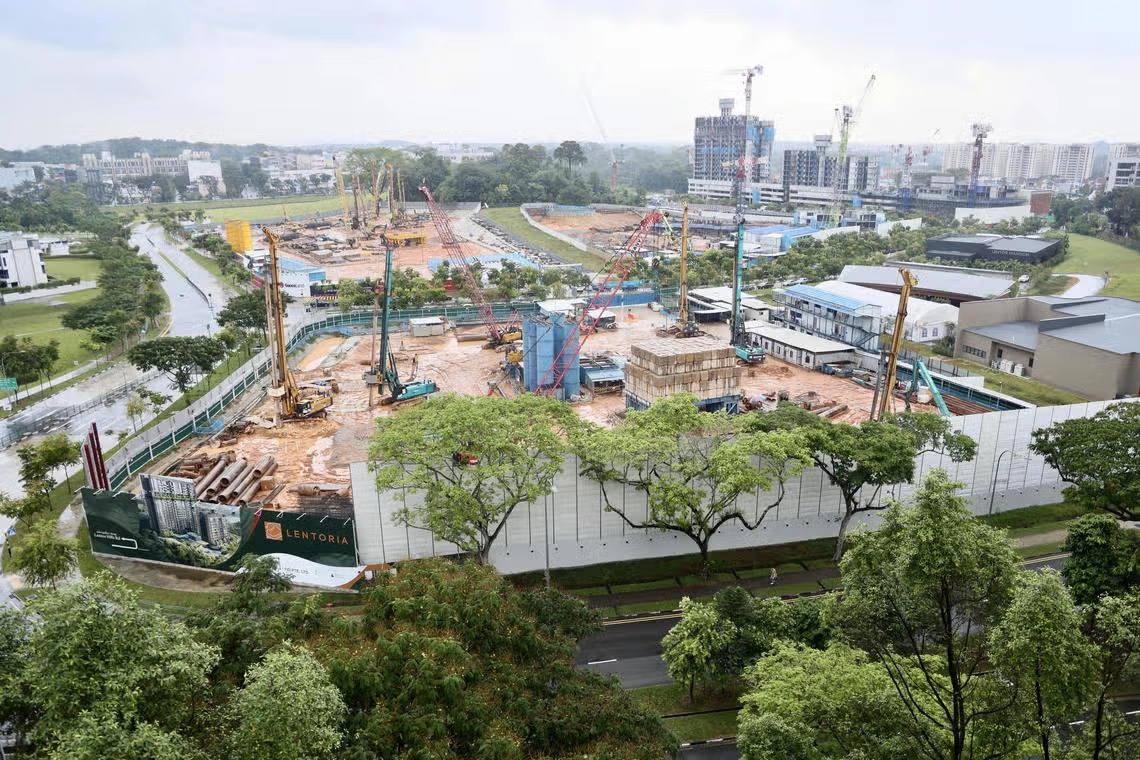
Nearly 2,800 Units Sold in Two Years: Take-Up Rate Tops 96%
As of 9 May 2025, a total of 2,942 units have been launched across six developments in Lentor, with 2,835 units snapped up, representing an outstanding 96% sales rate. While individual projects such as Lentoria experienced a more measured start, overall market absorption has exceeded expectations. In particular, GuocoLand’s Lentor Modern and Lentor Mansion saw over 80% of units sold during their launch weekends, underscoring strong homebuyer appetite for integrated transport connectivity and self-contained lifestyle amenities.
In terms of pricing trends, average prices have grown by around 5%, with several transactions crossing the S$2,000 psf threshold—cementing a new pricing benchmark for the Outside Central Region (OCR) market.

Land Prices Fall Over 20%: Developers Turn Cautious at GLS Tenders
Despite sustained end-user interest, the tender for the latest site—Lentor Gardens in April 2024—drew only two bids, closing at a land rate of S$920 psf per plot ratio (psf ppr). This is a 24% discount compared to the S$1,204 psf ppr achieved by the Lentor Modern site in 2021, signalling growing developer caution over supply-demand dynamics in the area.
This shift is also partly attributed to the harmonisation of gross floor area (GFA) definitions, which reduced saleable efficiency in later launches, thereby moderating developers' land bids.
Cluster Housing Precincts: A New Blueprint for Urban Renewal?
Lentor's transformation from a quiet enclave to a property hotspot is not merely a sales success; it serves as a blueprint for residential cluster planning. As successive developments debuted, market acceptance solidified. This momentum created a degree of 'fear of missing out' (FOMO) among undecided buyers, driving rapid sales conversion.
This master-planned, phased land sale strategy enables the government to coordinate infrastructure delivery—such as parks, commercial amenities, MRT links, and schools—using private residential development as a catalyst for comprehensive urban renewal.
Additionally, the sharp contraction of new OCR private housing supply between 2021 and 2023 funnelled substantial pent-up demand directly into Lentor, serving as another key driver behind its stellar sales figures.
Underlying Challenges Behind the Success
Nonetheless, property analysts caution that cluster-style master planning is not a one-size-fits-all solution:
High Product Homogeneity: Future sellers and landlords will face direct competition from multiple neighbouring developments offering similar unit layouts and facilities;
Subdued Tender Participation: Releasing too many sites in close succession within the same area can cause land tender fatigue among developers;
Density and Congestion Concerns: Without synchronised infrastructure upgrades, dense cluster living risks compounding local traffic and noise issues.
Policymakers must strike a fine balance between the pace of land supply and the market’s organic absorption capacity.
After Lentor, Which Enclave Is Next?
Beyond Lentor, several emerging precincts across Singapore are embracing similar cluster development patterns, including Tampines Street 86 / Tampines Avenue 1, Media Circle, and River Valley / Zion Road.
When executed with strategic urban planning, these clusters will deliver more than just new homes—they have the potential to anchor Singapore's next vibrant lifestyle hubs and thriving new communities.