News
Private Home Price Growth Rebounds to 3.2% in 1Q 2023
According to data released by the Urban Redevelopment Authority (URA) on 3 April, Singapore's private residential property prices rose by 3.2% quarter-on-quarter (q-o-q) in 1Q2023, accelerating from the 0.4% increase recorded in the previous quarter. Compared to the same period last year, prices grew by 11.3%.
The sustained increase in private home prices reflects that underlying housing demand remains robust, despite economic headwinds such as rising interest rates and slowing economic growth, alongside the hike in Buyer's Stamp Duty (BSD) for higher-value properties.
The accelerated price growth mirrors the market's resilience following the cooling measures announced in September 2022. The resurgence in private home price momentum in 1Q2023 suggests that the latest round of cooling measures has not sounded an alarm for the residential property market.
Prices for both landed and non-landed properties rose last quarter, posting q-o-q growth rates of 5.7% and 2.5%, respectively.
The surge in landed home prices was primarily driven by sales at Bukit Sembawang's 132-unit Pollen Collection in Seletar Hills.
Since its launch in October 2022, take-up for the development has doubled to eight units. The median price of its terraced houses increased from $1,893 psf in 4Q2022 to $2,199 psf in 1Q2023.
Supported by strong demand, the growth of landed home prices quickened from the 0.6% q-o-q increase recorded in 4Q2022. Buyers remain resolute in their desire to secure this scarce housing typology amidst Singapore's high-rise landscape, even if it entails paying a higher price tag.
Non-landed private residential prices also expanded at a faster clip compared to the previous quarter, which had seen a 0.3% q-o-q growth. Price growth in 1Q2023 was spearheaded by the Rest of Central Region (RCR), where prices climbed 4% q-o-q, up from a 3.1% gain in the previous quarter. This growth was boosted by new launches last quarter, including the 270-unit Terra Hill on Yew Siang Road, which set a new price benchmark of $2,650 psf for the neighbourhood during its launch weekend in February.
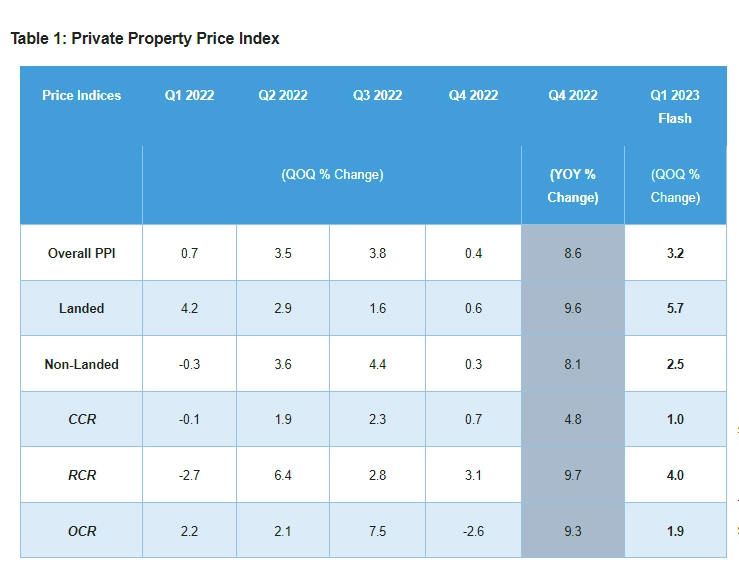
Prices in the Outside Central Region (OCR) rose by 1.9%, reversing a 2.6% decline in 4Q2022. The price increase was supported by the launches of Sceneca Residence in Tanah Merah and The Botany at Dairy Farm along Dairy Farm Walk, which achieved median prices of $2,072 psf and $2,070 psf, respectively.
In the Core Central Region (CCR), non-landed home prices ticked up 1% q-o-q, compared to a 0.7% increase in the preceding quarter. Launches of ongoing projects in the CCR saw an uptick as the price gap between the CCR and the OCR/RCR narrowed.
In terms of transaction volume, based on caveats lodged as of 3 April, 1,178 new homes were sold in 1Q2023. This is a 70.7% increase from the 690 units sold in 4Q2022, although these numbers remain "well below" historical averages.
More foreigners returned to the local residential property market in 1Q2023. Based on data as of 31 March, foreign buyers picked up 127 out of 1,403 units sold in new launches. The most popular projects among foreigners in 1Q2023 were Rivière (21 units), Klimt Cairnhill (20 units), Perfect Ten (10 units), Leedon Green (7 units), Pullman Residences Newton (7 units), and The Botany at Dairy Farm (5 units).
Looking ahead, the more cautious sentiment observed among home buyers may continue to prevail in the coming months amid elevated interest rates, tighter financing conditions, and an economic slowdown. Nonetheless, with upcoming launches such as Tembusu Grand, The Continuum, and Lentor Hills Residences likely to drive demand, the full-year forecast of 7,500 to 8,500 new private home sales for 2023 remains unchanged for now.
Private home prices are still anticipated to register positive growth this year, albeit at a moderated pace of around 3% to 5% compared to last year's 8.6% surge. Prices will be underpinned by several factors, including a stable labour market, continued HDB upgrader demand spurred by rising HDB resale prices, China's reopening, and lean unsold inventory levels.