News
March new home sales rise 13.9% month-on-month
According to data released by the URA on 17 April, a total of 492 new private homes (excluding Executive Condominiums, or ECs) were sold in March 2023. This represents a 13.9% increase from the 432 units sold in February, but a 24.8% decline compared to the 654 units transacted a year ago.
The 492 new homes sold were 43.8% below the five-year average for March (876 units). This brings new home sales for the first quarter of 2023 to 1,318 units, down 29.9% year-on-year from 1,880 units in 1Q 2022.
Buying momentum has slowed markedly compared to early 2022, as purchasing sentiment turned cautious amid record-high interest rates and an economic slowdown.
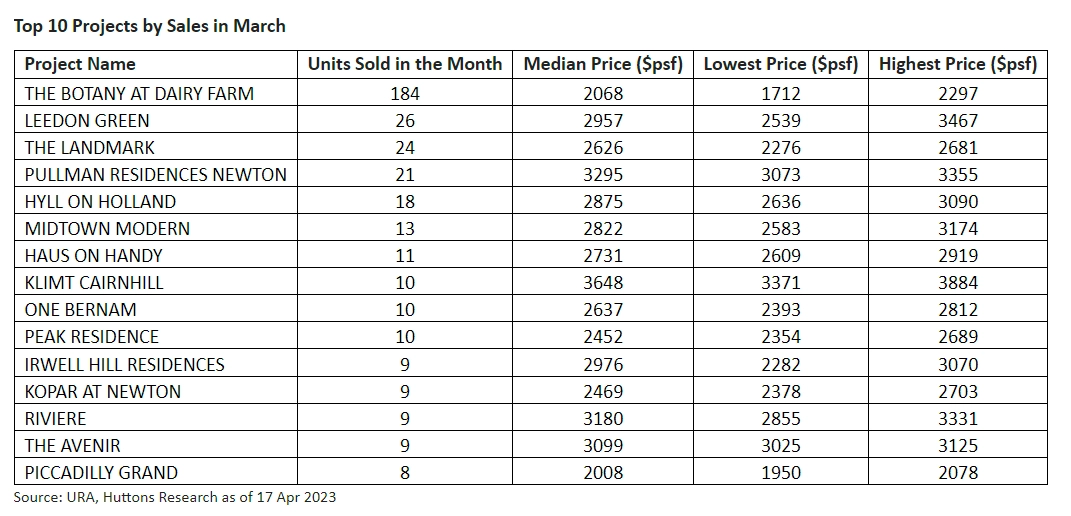
In March, The Botany at Dairy Farm in the Outside Central Region (OCR) led sales, moving 184 units at a median price of $2,068 psf during its launch.
Units sold at The Botany at Dairy Farm accounted for 37.4% of total sales in March, driving the OCR's share of transactions up to 46.7% for the month.
The Core Central Region (CCR)—representing luxury and prime homes—was the next most active segment, with 197 units (40%) transacted. CCR projects dominated the top 10 best-selling developments in March.
Compelling Value Proposition in the CCR
The narrowing price gap between private homes in the Core Central Region (CCR) and the Rest of Central Region (RCR) has turned prime CCR properties into an attractive proposition for buyers.
The median price gap for all non-landed residential properties between the CCR and RCR shrank from 44.6% in January to 30.5% in February and further to 24.4% in March.
Cooling measures and demand shifting towards more affordable market segments have tempered price upside for non-landed homes in the CCR. Meanwhile, prices in the RCR have risen at a faster clip, underpinned by stronger market demand and new projects launched at benchmark pricing.
Key projects driving CCR new home sales included Leedon Green, which transacted 26 units in March at a median price of $2,957 psf; Pullman Residences Newton, with 21 units sold at a median price of $3,295 psf; and Hyll on Holland, which shifted 18 units at a median price of $2,875 psf.
The top-selling projects in the RCR were The Landmark (24 units at a median price of $2,626 psf), Riviere (nine units at a median price of $3,180 psf), and Piccadilly Grand (eight units at a median price of $2,008 psf). Together, they accounted for 63% of sales in the submarket for the month.
New Home Prices Strengthen in March
New home prices strengthened visibly in March. Seven of the top 10 best-selling projects—namely Leedon Green, The Landmark, Pullman Residences Newton, Hyll on Holland, Klimt Cairnhill, Peak Residence, and One Bernam—saw prices rise by an average of 2.6% month-on-month.
With unsold inventory dwindling, developers have shown greater confidence in raising prices on the back of resilient market demand.
Current buying patterns appear to be largely supply-led rather than demand-driven, heavily dependent on the projects launched within the month.
The higher Buyer's Stamp Duty (BSD) rates announced in Budget 2023 have to some extent moderated overall ticket sizes. The share of new private homes sold at $1.5 million and above fell from 95% in February to 72% in March.
Developers may increasingly pivot towards one- and two-bedroom configurations in upcoming launches to mitigate the price quantum and psychological impact of higher BSD rates on mainstream homebuyers.
At The Botany at Dairy Farm, one- and two-bedroom units were nearly snapped up entirely. Investors flocked to these layouts, drawn by rental demand from the neighbouring German European School Singapore (GESS). Smaller households also favoured two-bedroom units, while upgraders leaned towards three-bedroom configurations.
Uptick in Foreign Buyers
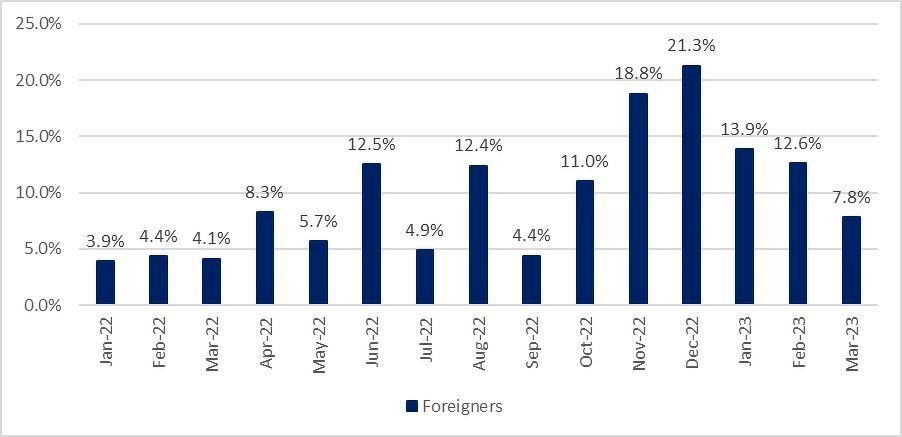
Foreign buyers accounted for 38 transactions (7.8%) of new home sales in March. Among units purchased in the CCR during the month, foreign buyers made up 73.7%.
Although China has dismantled most of its Covid-19 restrictions, it may still take some time for foreign demand to stage a more pronounced recovery.
The location of new launches also influences the balance between foreign and local demand. Recent launches in city-fringe and suburban locations tend to appeal predominantly to local buyers.
Upcoming Condominium Launches
Projects slated for launch in April and May include the 275-unit Blossoms By The Park (RCR), the 816-unit The Continuum along Thiam Siew Avenue (RCR), Newport Residences (CCR), the 598-unit Lentor Hills Residences (OCR), and the 732-unit The Reserve Residences (OCR).
Supported by a healthy pipeline of new launches this year, total new home sales are projected to reach 8,000 to 9,000 units in 2023. However, with resale market momentum tapering off and financing costs remaining elevated, risks remain tilted to the downside.
While the rental market faces headwinds from a surge in completions this year and in 2024, pricing momentum remains supported as elevated land and construction costs push new projects to launch at higher price points.
Amid mounting economic headwinds, overall private home prices are projected to rise by 5% to 7% in 2023, following an 8.6% gain in 2022.