News
Chinese New Year New Launch Hiatus: How Is the Market Shifting?
February New Home Sales Tumble Amid Severe Supply Crunch
Following a sales rebound in January, Singapore's new private residential market saw a sharp pullback in February.
According to data released by the Urban Redevelopment Authority (URA) on 16 February, developers moved 246 new private homes (excluding Executive Condominiums, or ECs) in February, sliding 47.2% from January.
Year-on-year, sales plunged by 84.6% compared to the 1,575 units transacted in the same period last year.

New Launch Supply Hits Lowest Level Since 2007
The primary factor driving the sales slump was an acute scarcity of fresh supply.
Only 15 units were launched in February, tumbling 98.1% month-on-month and 99.1% year-on-year—marking the lowest monthly tally since 2007.
Market watchers widely noted that this pullback was well within expectations.
February coincided with the Lunar New Year festive lull, a period typically characterized by subdued marketing campaigns and lower viewing activity. The lacklustre monthly performance was primarily driven by a lack of fresh launches rather than waning underlying demand.
Prime CCR Projects Maintain Steady Demand
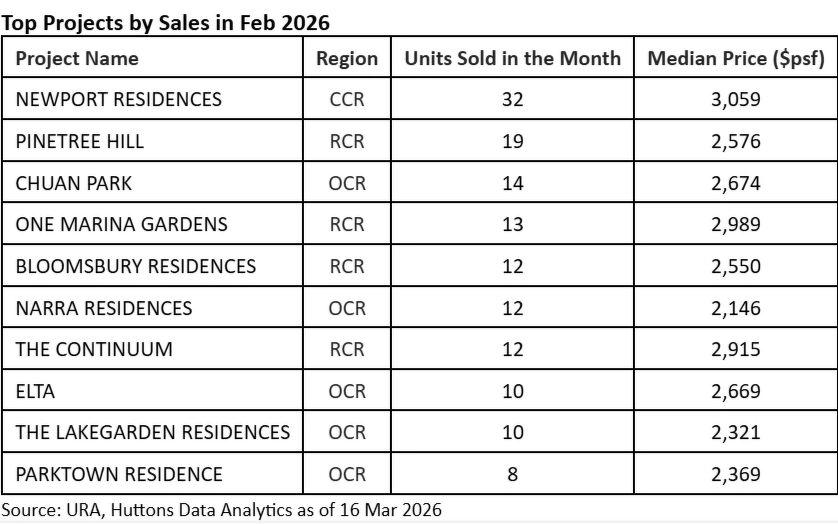
Amid muted market activity, Newport Residences emerged as February's best-selling project.
The development sold 32 units during the month at a median price of around $3,059 psf.
This marks the second straight month that the project has topped sales charts, having moved 132 units in January.
Developed by City Developments Limited (CDL), the freehold development along Anson Road achieved a 57% take-up rate upon its launch on 31 January. To date, it has sold approximately 169 units, representing 69% of its total inventory.
Analysts noted that its performance reaffirms the enduring appeal and resilience of prime developments in the Core Central Region (CCR).
RCR Leads Market Sales
From a geographical standpoint, sales in February were primarily led by the Rest of Central Region (RCR).
The RCR accounted for over 41% of total transactions, followed by the Outside Central Region (OCR) at 32.5%, and the CCR at 25.6%.
Four out of the top 10 best-selling developments in February came from the RCR.

Among them, Pinetree Hill moved 19 units at a median price of around $2,576 psf.
Other noteworthy performers included:
One Marina Gardens (13 units, $2,989 psf)
Bloomsbury Residences (12 units, $2,550 psf)
The Continuum (12 units, $2,915 psf)
The strong appeal of RCR projects stems from their compelling balance of pricing, prime city-fringe location, and comprehensive amenities, offering a coveted 'sweet spot' between the CCR and OCR.
Higher Proportion of Higher-Quantum Deals
Another notable trend in February was the rise in the proportion of higher-quantum unit transactions.
Units priced below $2.5 million accounted for only 42% of total new home sales, down substantially from 66% in January.

Market observers pointed out that in the absence of new project launches, unsold inventories mostly comprise larger-format and premium units, which naturally lifted the overall price quantum profile.
EC Demand Remains Resilient
In contrast to private homes, executive condominium (EC) demand held firm.
A total of 20 EC units were transacted in February, with Otto Place fully sold out after its final 10 units were snapped up.
Coastal Cabana is currently the only EC development with unsold inventory on the market, moving 9 units in February at an average price of around $1,804 psf.
To date, Coastal Cabana has sold 517 units, or 69.1% of its total offerings.
Analysts anticipate that the upcoming Rivelle Tampines EC will continue to see keen buyer interest.
The development attracted over 8,000 visitors during its preview in March, demonstrating strong underlying appetite from local buyers.
Supply Inflow Expected to Re-energise the Market
Looking ahead, market activity is expected to pick up momentum over the coming months as new supply gradually recovers with a steady pipeline of project launches.
River Modern, launched in March, sold 410 units, making it the strongest-selling CCR new launch year-to-date in 2026.
Other upcoming launches in the pipeline include:
Pinery Residences (588 units)
Vela Bay at Bayshore (515 units)
Hudson Place Residences (325 units)
Tengah Garden Residences (863 units)
Market Outlook: Resilient Demand with Modest Price Growth
Despite ongoing geopolitical tensions in the Middle East, analysts generally view the impact on the local real estate market as limited.
Market research consultancies noted that buyer sentiment remains broadly stable, and new launch demand is expected to stay resilient.
Nonetheless, industry observers caution that inflation and elevated construction costs could continue to exert upward pressure on prices.
Full-year new private home sales for 2026 are projected to range between 8,000 and 10,000 units, with home prices expected to rise modestly by 2% to 5%.