News
CCR Prices Lower Than RCR? The Inverted Private Home Pricing Trend Worth Watching
Hot New Private Home Sales! February Volumes Surge to 13-Year High, Led by the Mass Market
According to data released by the Urban Redevelopment Authority (URA) on 17 March, new private home sales (excluding ECs) reached a robust 1,575 units in February 2025, surging 45.4% month-on-month. This marks the strongest February sales volume since February 2012. Including Executive Condominiums (ECs), total developer sales reached 1,604 units.
Sales in First Two Months Surpass First Eight Months of Last Year Combined
Developers moved 2,658 units (excluding ECs) in the first two months of the year, a figure that took eight months to achieve last year—pointing to a notably accelerated market recovery in 2025.

The sales boom was primarily driven by two launches in the Outside Central Region (OCR):
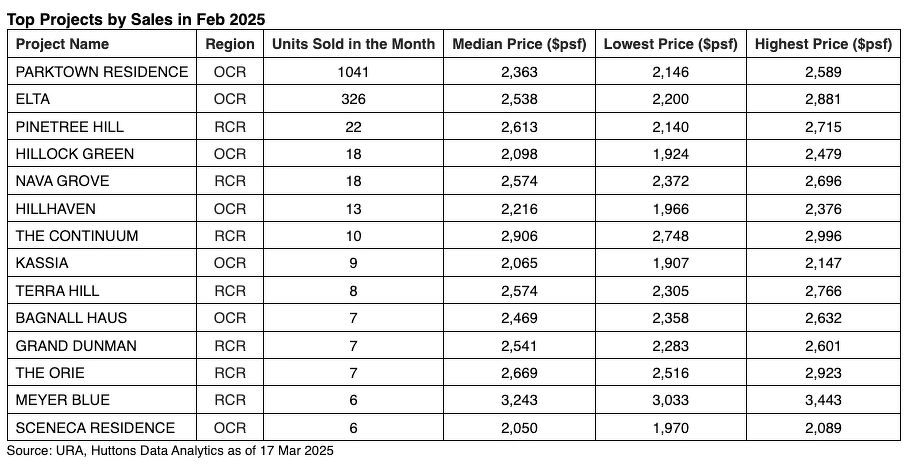
Parktown Residence (Tampines North): 1,041 out of 1,193 units sold (87% take-up rate) at a median price of $2,363 psf.
ELTA (Clementi): 326 out of 501 units sold (65.1%) at a median price of $2,538 psf.
Both suburban developments are located in estates that have seen no new private supply for at least five years, with pent-up demand and scarcity powering their stellar performance.
Developers launched 1,694 units in February, an 89% increase month-on-month. OCR projects accounted for 1,452 units, or 92% of total sales, marking the strongest single-month performance for the OCR since July 2015.
Market Overview: OCR Dominates While CCR Sees Just 25 Units Sold
Rest of Central Region (RCR): 98 units sold, accounting for 6.2% of total transactions. Pinetree Hill led with 22 units sold at a median price of $2,613 psf.
Core Central Region (CCR): Only 25 units sold, representing 1.6%.
The top-selling CCR project was 19 Nassim, which moved 5 units at a median price of $3,372 psf.
One Bernam (launched in 2021) also moved 4 units and is now fully sold out.

Local Buyers Anchor the Market, Foreign Buyers Emerge in Luxury Deals
Data reveals Singapore Citizens accounted for 92.4% of new private home purchases, while Permanent Residents (PRs) made up 6.9%. Foreign buyers picked up 11 units, including two ultra-luxury units at 32 Gilstead transacted at $14.47 million and $14.61 million respectively.
Record-Breaking: 603 New OCR Homes Transacted Above $2 Million
A staggering 603 new units in the OCR were transacted at $2 million and above in February, with 397 from Parktown Residence, 145 from ELTA, and another 16 from Hillock Green.
Market Dislocation? Some OCR New Launches Fetch Higher PSF Prices Than RCR Projects
PSF pricing in certain OCR launches has decoupled from traditional regional pricing tiers.
The Collective at One Sophia (CCR): Average $2,743 psf
Union Square Residences (RCR): Average $3,175 psf
The Orie (RCR): Average $2,734 psf
Recent OCR Projects (PSF): The Chuan Park: $2,589 psf; ELTA: $2,544 psf; Bagnall Haus: $2,489 psf; compared to RCR's Nava Grove: $2,460 psf.
This trend is driven by attributes such as prime suburban micro-locations, comprehensive integrated amenities, strong demand from HDB upgraders, and the city-fringe proximity of certain developments.
As projects on the fringe of the CCR like One Marina Gardens enter the market, the price gap between regions could narrow further.
Strong Momentum to Continue: Q1 Sales Projected at 3,200 Units, A Three-Year High
March launches—including Lentor Central Residences (477 units), Aurea (188 units), and Aurelle of Tampines EC (760 units)—have collectively sold over 1,150 units by mid-March, setting the stage for a strong close to Q1.
Consequently, Q1 new home sales (excluding ECs) are projected to cross 3,200 units, making it the strongest first-quarter performance since 2021.
Q2 Outlook: Pipeline Packed with New Launches, but Performance Will Diverge
Upcoming launches in the pipeline include: Bloomsbury Residences (358 units); One Marina Gardens (937 units); W Residences Singapore - Marina View (638 units); and Arina East Residences (107 units).
Despite the strong start to the year, performance is expected to diverge based on micro-location and product attributes.